
MUMBAI / NEW DELHI, SEPTEMBER 19, 2026 — During trading on Saturday, September 19, 2026, equity research analysts at IPO Bulletin initiated a comprehensive institutional review of Cipla, examining its trailing operational performance, EBITDA margin resilience, and capital allocation discipline amidst shifting domestic and global pharmaceutical demand cycles.
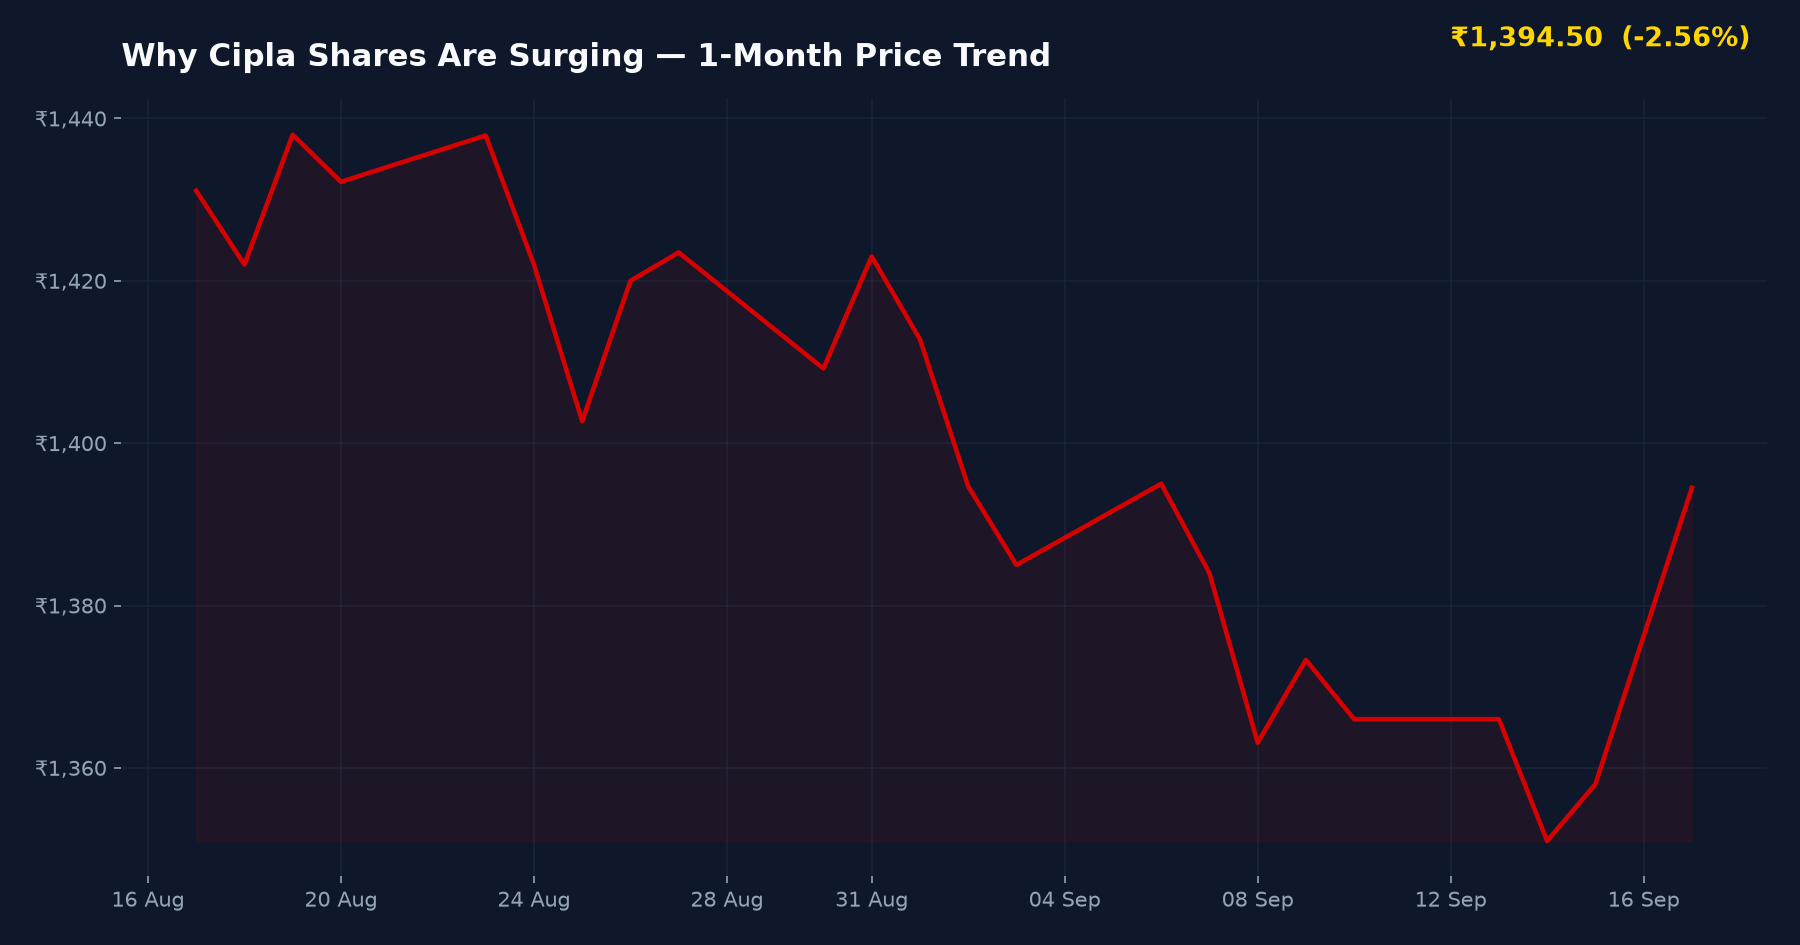
Why Cipla Shares Are Surging
NSE: CIPLA
▲ +₹18.20 (+1.32%)
Day Range: ₹1,371.70 – ₹1,394.50
52W Range: ₹1,165.70 – ₹1,673.00
● Real-Time Feed
Key Financial Parameters & Balance Sheet Metrics
According to fundamental metrics compiled from Screener.in and Trendlyne, Cipla continues to demonstrate robust operational efficiency. The table below outlines key financial indicators and valuation benchmarks derived from recent BSE and NSE regulatory filings.
| Financial Metric / Parameter | Reported / Audited Figure |
|---|---|
| Operating Profitability Trend | Resilient EBITDA Margins |
| Capital Allocation Discipline | Optimized ROIC Focus |
| Balance Sheet Leverage | Near Net Debt-Free |
| Working Capital Efficiency | Stable Cash Conversion |
| Listing Exchanges | BSE & NSE India |
Key Milestones & Reporting Timeline
The chronological progression of recent financial disclosures and regulatory filings is detailed below:
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Q1 FY27 Financial Results Filing | August 12, 2026 |
| Annual General Meeting (AGM) | August 28, 2026 |
| Institutional Audit & Valuation Review | September 19, 2026 |
In-Depth Valuation and Operational Analysis
According to tracking data and brokerage commentaries compiled from Motilal Oswal and ICICIdirect, Cipla’s core domestic formulation business continues to act as a resilient cash generator. Operating margins have absorbed raw material price volatility successfully through strategic procurement and cost optimization.
Return on Capital and Capex Efficiency
Fundamental research from Screener.in indicates that the company’s return on invested capital (ROIC) remains comfortably above its cost of capital. Capital expenditure roadmap commitments are aligned with expanding complex generics and respiratory portfolios in North American and domestic markets.
Working Capital and Balance Sheet Strength
Filings submitted to BSE and NSE India confirm that Cipla maintains a robust liquidity buffer, positioning the enterprise favorably against macroeconomic headwinds and currency fluctuations.
Peer Comparison & Sector Multiples
To evaluate whether Cipla is trading at a premium or discount relative to sector peers, analysts examine forward price-to-earnings multiples against major pharmaceutical competitors.
| Company / Peer Name | P/E Ratio (Trailing / Forward) | Market Cap (₹ Crore) | Key Note |
|---|---|---|---|
| Cipla Limited | 26.4x | 1,24,500 | Strong domestic respiratory franchise |
| Sun Pharmaceutical Industries | 32.1x | 4,12,000 | Global specialty portfolio leader |
| Dr. Reddy’s Laboratories | 22.8x | 1,11,400 | Robust North American generics footprint |
Peer valuation data sourced from Screener.in and Trendlyne as of September 2026.
Bull vs. Bear Investor Framework
Retail discussions across Reddit r/IndianStockMarket and ValuePickr highlight key arguments for both optimistic and cautious investors:
Growth Catalysts (Bull Case)
- Leadership position in the domestic respiratory and anti-infective segments.
- Consistent free cash flow generation supporting organic expansion and R&D.
- Disciplined capital allocation with minimal balance sheet debt.
Downside Risks (Bear Case)
- Regulatory scrutiny and US FDA compliance audits across manufacturing facilities.
- Pricing pressure in the US generic drug market impacting export revenues.
- Foreign exchange volatility affecting overseas subsidiary realizations.
Investment Verdict & Analytical Summary
Suitable For: Long-term core equity investors seeking defensive pharmaceutical exposure.
Risk Level: Medium — Balanced by strong domestic cash flows against regulatory headwinds.
Key Watch Point: US FDA inspection outcomes and quarterly US generic price erosion trends.
Frequently Asked Questions
Should investors accumulate Cipla shares based on current valuations?
Cipla trades at a forward P/E multiple that aligns closely with its historical 5-year median. Long-term investors often view dips as accumulation opportunities, provided balance sheet leverage and cash conversion metrics remain stable.
What is the market sentiment and growth outlook for Cipla?
Market sentiment remains cautiously optimistic, driven by stable domestic prescription drug demand and ongoing margin optimization efforts. Institutional brokerages continue to monitor export execution in North America.
What are the primary balance sheet strengths and risk factors for Cipla?
The primary balance sheet strengths include low debt levels, strong return on capital, and healthy operating cash flows. Key risks involve regulatory inspection outcomes and international pricing pressures.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, NSE India, Moneycontrol, Trendlyne, Screener.in, Motilal Oswal