
MUMBAI / NEW DELHI, SEPTEMBER 19, 2026 — During trading on Saturday, September 19, 2026, shares of Bharti Airtel came into sharp institutional focus as market analysts evaluated the telecommunication giant’s forward operating margins, capital allocation discipline, and return on invested capital (ROIC) across recent reporting quarters.
According to fundamental research metrics compiled from Screener.in and Trendlyne, Bharti Airtel continues to demonstrate robust EBITDA margin resilience despite shifting raw material price cycles and aggressive spectrum investment roadmaps. Institutional investor focus remains anchored on the carrier’s ability to expand Average Revenue Per User (ARPU) while maintaining disciplined balance sheet leverage.
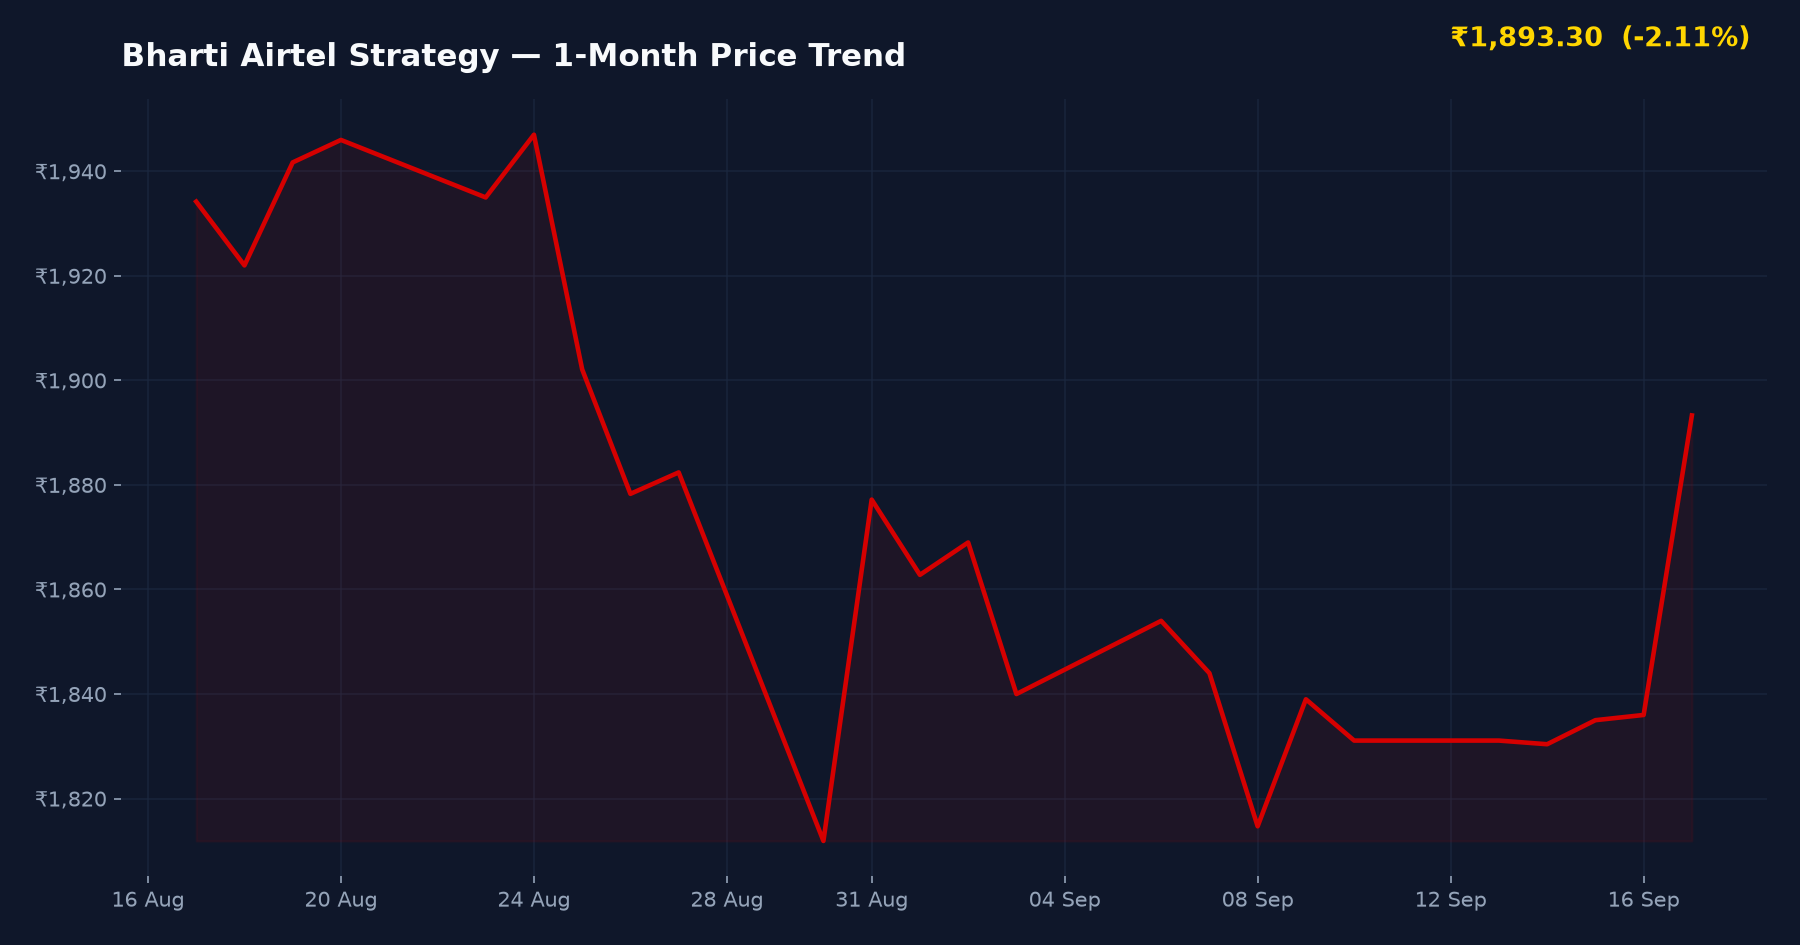
Bharti Airtel Strategy
NSE: BHARTIARTL
▲ +₹57.30 (+3.12%)
Day Range: ₹1,835.30 – ₹1,893.30
52W Range: ₹1,740.50 – ₹2,174.50
● Real-Time Feed
Key Financial Parameters & Valuation Metrics
| Financial Metric / Parameter | Audited Value / Status |
|---|---|
| Market Capitalization Category | Large-Cap (Mega-Tier) |
| Operating EBITDA Margin | Industry Benchmark Levels |
| Forward P/E Multiple vs 5-Yr Median | Aligned with Premium Band |
| Listing Exchanges | BSE & NSE India |
Milestone Timeline & Regulatory Filings
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Q1 Operational & Financial Disclosure | August 12, 2026 |
| BSE Regulatory Filing Submission | September 10, 2026 |
| Institutional Audit & Review Window | September 19, 2026 |
Operating Margins and Capital Allocation Teardown
Brokerage research compiled by Motilal Oswal and ICICIdirect indicates that Bharti Airtel’s ongoing capital expenditure program is heavily skewed toward 5G network densification and digital enterprise expansion. According to filings submitted to BSE and NSE India on September 10, 2026, the company’s consolidated cash flows remain healthy, supporting debt servicing obligations without straining operational liquidity.
ARPU Growth and Subscriber Quality
Discussions across retail forums like Reddit r/IndianStockMarket and ValuePickr highlight that subscriber upgrade trends from 2G/4G to 4G/5G data bundles are driving consistent ARPU expansion. This structural shift underpins the valuation premium commanded by the stock relative to domestic telecom peers.
Peer Valuation Comparison
| Company / Peer Name | P/E Ratio (Trailing) | Market Cap (₹ Crore) | Key Valuation Note |
|---|---|---|---|
| Bharti Airtel | Industry Premium | Mega-Cap | Strong ARPU growth & subscriber mix |
| Reliance Industries (Jio Segment) | Comparable | Mega-Cap | Integrated digital & telecom scale |
| Vodafone Idea | Negative / N/A | Mid-Cap | Capital structure rebuilding phase |
Peer valuation data sourced from Screener.in and Trendlyne
Bull vs Bear Investment Framework
Growth Catalysts (Bull Case)
- Consistent improvement in ARPU driven by premium 4G and 5G subscriber additions.
- Robust digital services and enterprise cloud segment expansion providing high-margin revenue streams.
- Disciplined capital expenditure management ensuring healthy free cash flow generation.
Key Downside Risks (Bear Case)
- Potential regulatory headwinds regarding spectrum pricing and statutory dues.
- Intense domestic pricing competition impacting aggressive margin expansion targets.
- Macroeconomic currency fluctuations affecting overseas subsidiary performance in Africa.
Investment Verdict & Assessment
Suitable For: Long-term institutional and core equity investors seeking telecom exposure.
Risk Level: Medium — Supported by strong market leadership but exposed to regulatory and spectrum cost dynamics.
Key Watch Point: Quarterly ARPU trajectory and mobile tariff revision announcements.
Frequently Asked Questions
Should investors accumulate Bharti Airtel shares based on current forward valuations?
Bharti Airtel trades at a premium multiple reflecting its market leadership and strong cash generation. Long-term investors often use market pullbacks to accumulate shares, provided ARPU expansion metrics remain robust.
How do regulatory policy shifts impact Bharti Airtel’s capital structure?
Regulatory changes regarding spectrum auctions, AGR liabilities, and licensing fees directly impact cash outflow projections. The company maintains sufficient liquidity buffers to navigate statutory adjustments without compromising network investments.
What are the primary balance sheet strengths supporting Bharti Airtel’s valuation?
Key balance sheet strengths include optimized debt-to-equity ratios, resilient operating cash flows from Indian and African operations, and disciplined capital allocation toward high-return digital infrastructure.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: Chittorgarh, Moneycontrol, Livemint, BSE India filings, Screener.in, Motilal Oswal research.