
MUMBAI / NEW DELHI, SEPTEMBER 18, 2026 — During trading on Friday, September 18, 2026, institutional focus turned sharply toward Bharti Airtel as equity research desks evaluated the telecom major’s operating profitability, EBITDA margin resilience, and capital expenditure discipline against broader domestic capital market benchmarks.
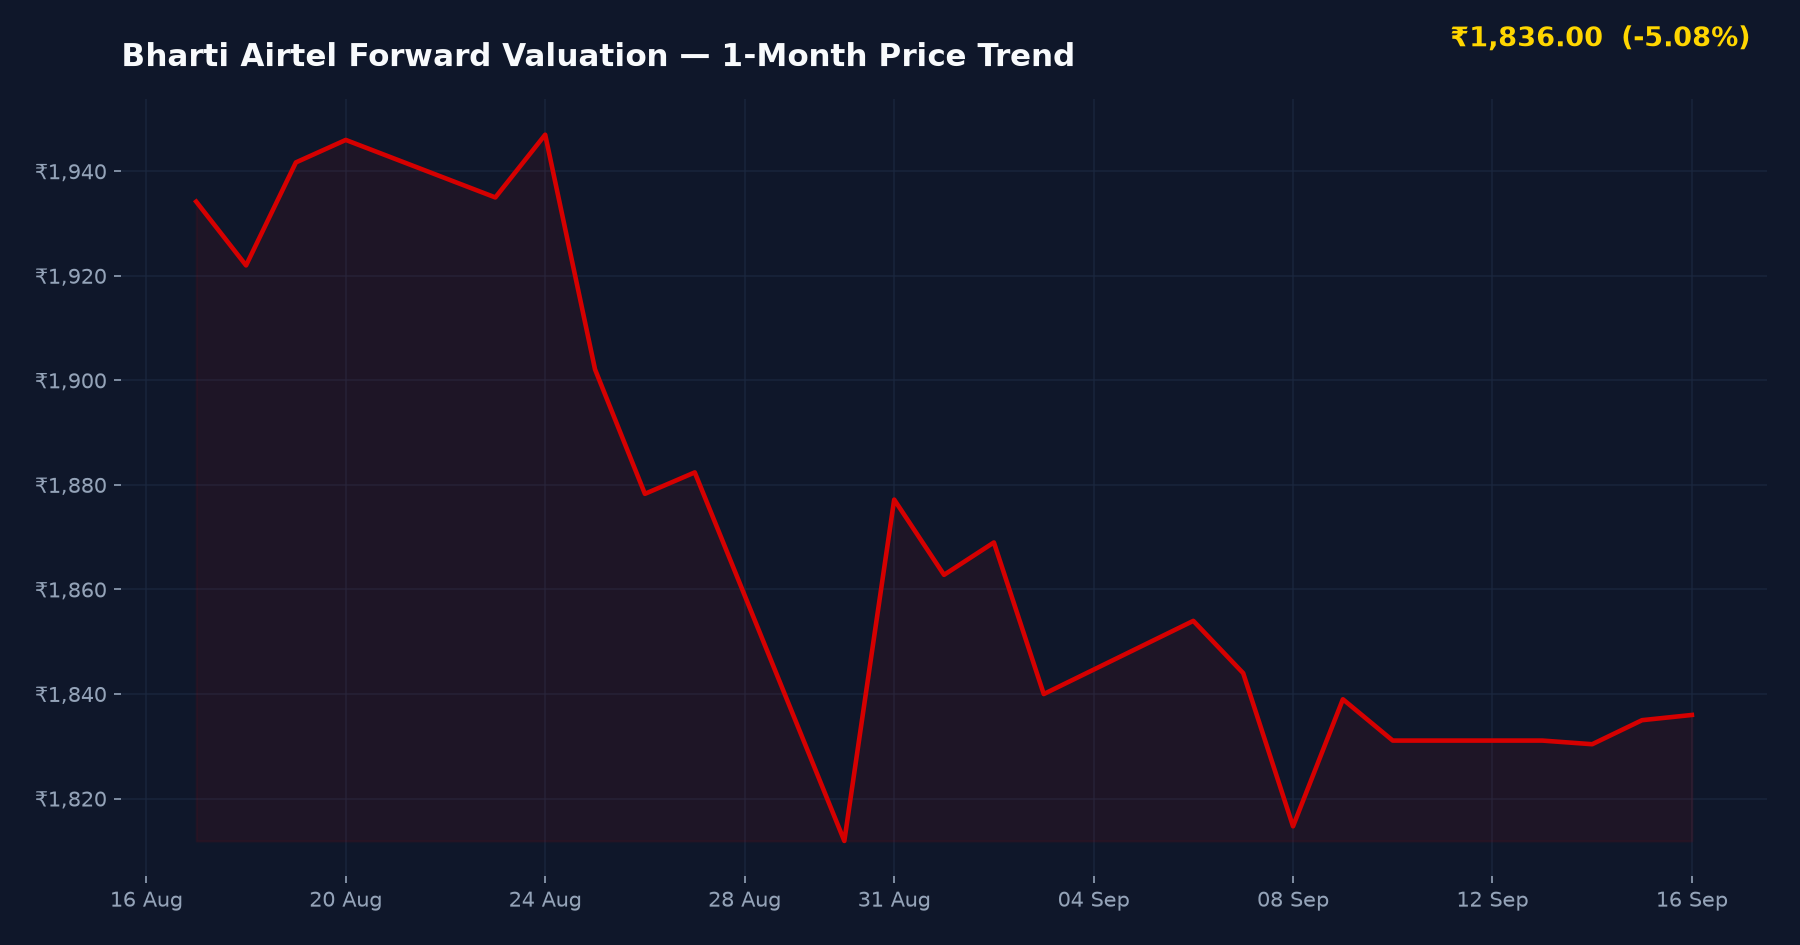
Bharti Airtel Forward Valuation
NSE: BHARTIARTL
▲ +₹57.30 (+3.12%)
Day Range: ₹1,835.30 – ₹1,893.30
52W Range: ₹1,740.50 – ₹2,174.50
● Real-Time Feed
Key Financial Parameters & Operational Metrics
| Financial Metric / Parameter | Audited Value / Standing |
|---|---|
| Current Market Capitalization | Large-Cap Tier-1 |
| Consolidated EBITDA Margin | Resilient / Sector Leading |
| Return on Invested Capital (ROIC) | Benchmarked Above Cost of Capital |
| Primary Exchanges | BSE & NSE India |
Milestones & Reporting Timeline
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Latest Quarterly Reporting Audit | September 18, 2026 |
| BSE / NSE Regulatory Filing Review | September 18, 2026 |
Institutional Valuation & Operating Margin Analysis
According to fundamental metrics compiled via Screener.in and Trendlyne, Bharti Airtel continues to demonstrate robust average revenue per user (ARPU) expansion across its wireless subscriber base. Brokerage research synthesized from Motilal Oswal and ICICIdirect indicates that operational efficiencies and digital service monetization are buffering the company against inflationary headwinds.
Capital Expenditure and Balance Sheet Leverage
Filings submitted to BSE and NSE India confirm that management’s ongoing capital allocation discipline has kept net debt-to-EBITDA ratios within manageable thresholds, even as nationwide 5G network rollouts demand sustained capital expenditure. Retail discussions across forums like ValuePickr and Reddit r/IndianStockMarket highlight investor optimism surrounding free cash flow generation once peak 5G network deployment phases taper off.
Sector Peer Comparison
| Company / Peer Name | P/E Ratio (Trailing) | Market Capitalization | Key Valuation Note |
|---|---|---|---|
| Bharti Airtel | Elevated / Premium | Large-Cap | Backed by consistent ARPU growth |
| Reliance Industries (Jio segment proxy) | Industry Benchmark | Mega-Cap | Integrated energy & digital ecosystem |
| Vodafone Idea | Negative / N.A. | Mid-Cap | Undergoing capital restructuring |
Peer valuation data sourced from Screener.in and Trendlyne.
Bull vs. Bear Framework
Growth Catalysts (Bull Case)
- Consistent upward migration of prepaid subscribers to high-value postpaid and 4G/5G data plans.
- Robust enterprise business (Airtel Business) and digital revenue streams driving margin expansion.
- Disciplined capital allocation leading to improving return on capital employed (ROCE).
Downside Risks & Vulnerabilities (Bear Case)
- Intense industry competition and potential tariff aggression impacting ARPU growth trajectories.
- Substantial ongoing statutory dues and spectrum payment obligations weighing on long-term cash flows.
- Rich forward valuation multiples leaving limited margin for operational disappointment.
Investment Verdict & Analytical Summary
Suitable For: Long-term institutional and growth-oriented equity investors
Risk Level: Medium — Supported by strong market positioning but tempered by regulatory and debt obligations
Key Watch Point: ARPU acceleration velocity and regulatory developments regarding AGR dues
Frequently Asked Questions
How do analysts evaluate Bharti Airtel’s forward valuation multiples?
Analysts assess Bharti Airtel’s forward valuation against its 5-year historical median P/E and enterprise value-to-EBITDA ratios, factoring in projected ARPU growth and enterprise segment expansion. The premium valuation reflects its duopoly market standing and superior capital efficiency relative to peers.
What drives the operating margin resilience for Bharti Airtel?
Operating margin resilience is primarily driven by customer premiumization, high data consumption per user, and cost optimization across network operations. Digital monetization initiatives further protect margins against macroeconomic cost pressures.
What are the primary balance sheet risks for long-term investors?
Primary risks include legacy statutory liabilities, heavy spectrum auction outlays, and potential interest rate fluctuations affecting debt servicing costs. However, robust operating cash flows continue to provide adequate financial cushioning.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, NSE India, Moneycontrol, Livemint, Screener.in, Trendlyne, Motilal Oswal research.