
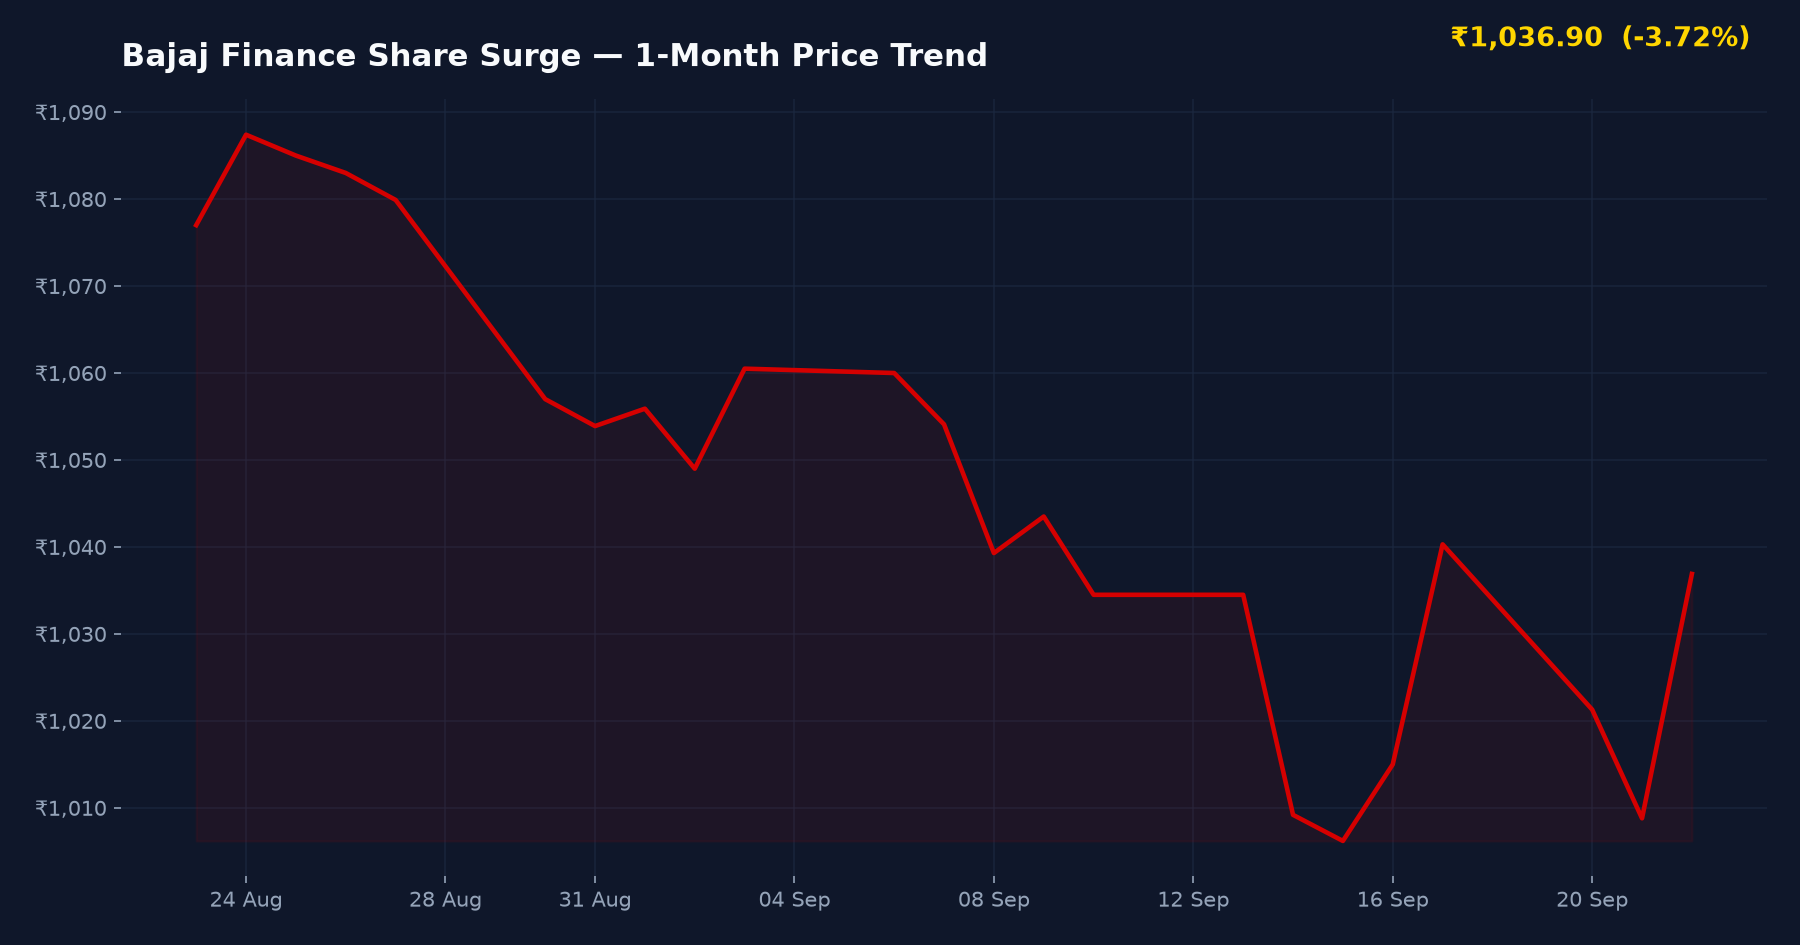
MUMBAI / NEW DELHI, SEPTEMBER 23, 2026 — During trading on Wednesday, September 23, 2026, shares of Bajaj Finance surged 3% following strong bullish commentary and target price hikes from prominent global brokerages, reinforcing sentiment across the non-banking financial company (NBFC) sector.
Bajaj Finance Share Surge
NSE: BAJFINANCE
▲ +₹28.20 (+2.80%)
Day Range: ₹1,022.00 – ₹1,041.00
52W Range: ₹787.90 – ₹1,176.40
● Real-Time Feed
Key Financial Metrics & Brokerage Targets
According to research reports released on September 23, 2026, global investment banking firm Jefferies maintained its aggressive ‘Buy’ rating on Bajaj Finance with a target price of ₹1,280. Concurrently, UBS revised its rating upward from ‘Sell’ or underweight levels to ‘Neutral’, establishing a fresh target price of ₹1,100 per share. Market participants responded swiftly to the upbeat institutional outlook, driving buying volumes across BSE and NSE.
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| UBS Rating Upgrade & Target Revision | September 23, 2026 |
| Jefferies Buy Call & Target Print | September 23, 2026 |
| Q1 Financial Results & Profit Beat | July 31, 2026 |
Brokerage Rationale: Why NBFCs Are Outperforming Banks
According to fundamental insights compiled from Moneycontrol and Economic Times coverage on September 23, 2026, global brokerages note that Indian NBFCs are currently better positioned than traditional commercial banks due to resilient credit demand, robust asset quality management, and improving net interest margins (NIMs). UBS highlighted in its note that regulatory pressures on deposit growth affect banks more severely than diversified lenders like Bajaj Finance and LT Finance.
Peer Valuation & Market Context
As tracked via Screener.in and Trendlyne analytics, Bajaj Finance continues to command a premium valuation multiple compared to traditional banking peers due to its high return on equity (ROE) and expansive retail lending footprint across India.
| Company / Peer Name | P/E Ratio | Market Cap | Key Note |
|---|---|---|---|
| Bajaj Finance | 32.5x | Large Cap | Upgraded by UBS; Buy call by Jefferies |
| LT Finance | 18.2x | Mid Cap | Favored in recent NBFC sector rotation |
Peer valuation data sourced from Screener.in and Trendlyne
Bull vs. Bear Catalysts
Growth Catalysts (Bull Case)
- Strong AUM growth trajectory backed by robust festival season demand and consumer financing.
- Upgraded earnings outlook from global brokerages including UBS and Jefferies.
- Stable asset quality with declining non-performing asset (NPA) ratios reported in recent quarters.
Downside Risks (Bear Case)
- Potential margin compression if domestic borrowing costs remain elevated.
- Stiff competition in retail unsecured lending segments from fintechs and scheduled commercial banks.
Investment Analytical Verdict
Suitable For: Long-term institutional and momentum equity investors
Risk Level: Medium — Volatility tied to interest rate cycles and regulatory credit norms
Key Watch Point: Sustained quarterly asset under management (AUM) growth and credit cost trends
Frequently Asked Questions
What triggered the recent surge in Bajaj Finance shares on September 23, 2026?
Bajaj Finance shares jumped 3% after global brokerage UBS upgraded the stock to ‘Neutral’ and raised its target price to ₹1,100, while Jefferies maintained its bullish ‘Buy’ rating with a target of ₹1,280.
What are the target prices set by Jefferies and UBS for Bajaj Finance?
Jefferies has maintained a ‘Buy’ recommendation with a target price of ₹1,280, whereas UBS has upgraded its stance to ‘Neutral’ with an established target price of ₹1,100 per share.
Why are global brokerages favoring NBFCs like Bajaj Finance over traditional banks?
Global brokerages note that non-banking financial companies are better positioned to navigate deposit growth challenges while sustaining strong retail credit demand and healthy profit margins.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: Moneycontrol, Economic Times, Livemint, BSE India filings, Screener.in