
MUMBAI / NEW DELHI, SEPTEMBER 19, 2026 — During trading on Saturday, September 19, 2026, shares of Dixon Technologies (India) Limited registered significant market attention following comprehensive fundamental disclosures regarding its smartphone manufacturing volume expansion under the central Production Linked Incentive (PLI) scheme. According to regulatory filings submitted to the BSE and NSE India, the company’s aggressive capacity scaling alongside global brand partnerships has fundamentally altered its medium-term financial trajectory.
Dixon Technologies
NSE: DIXON
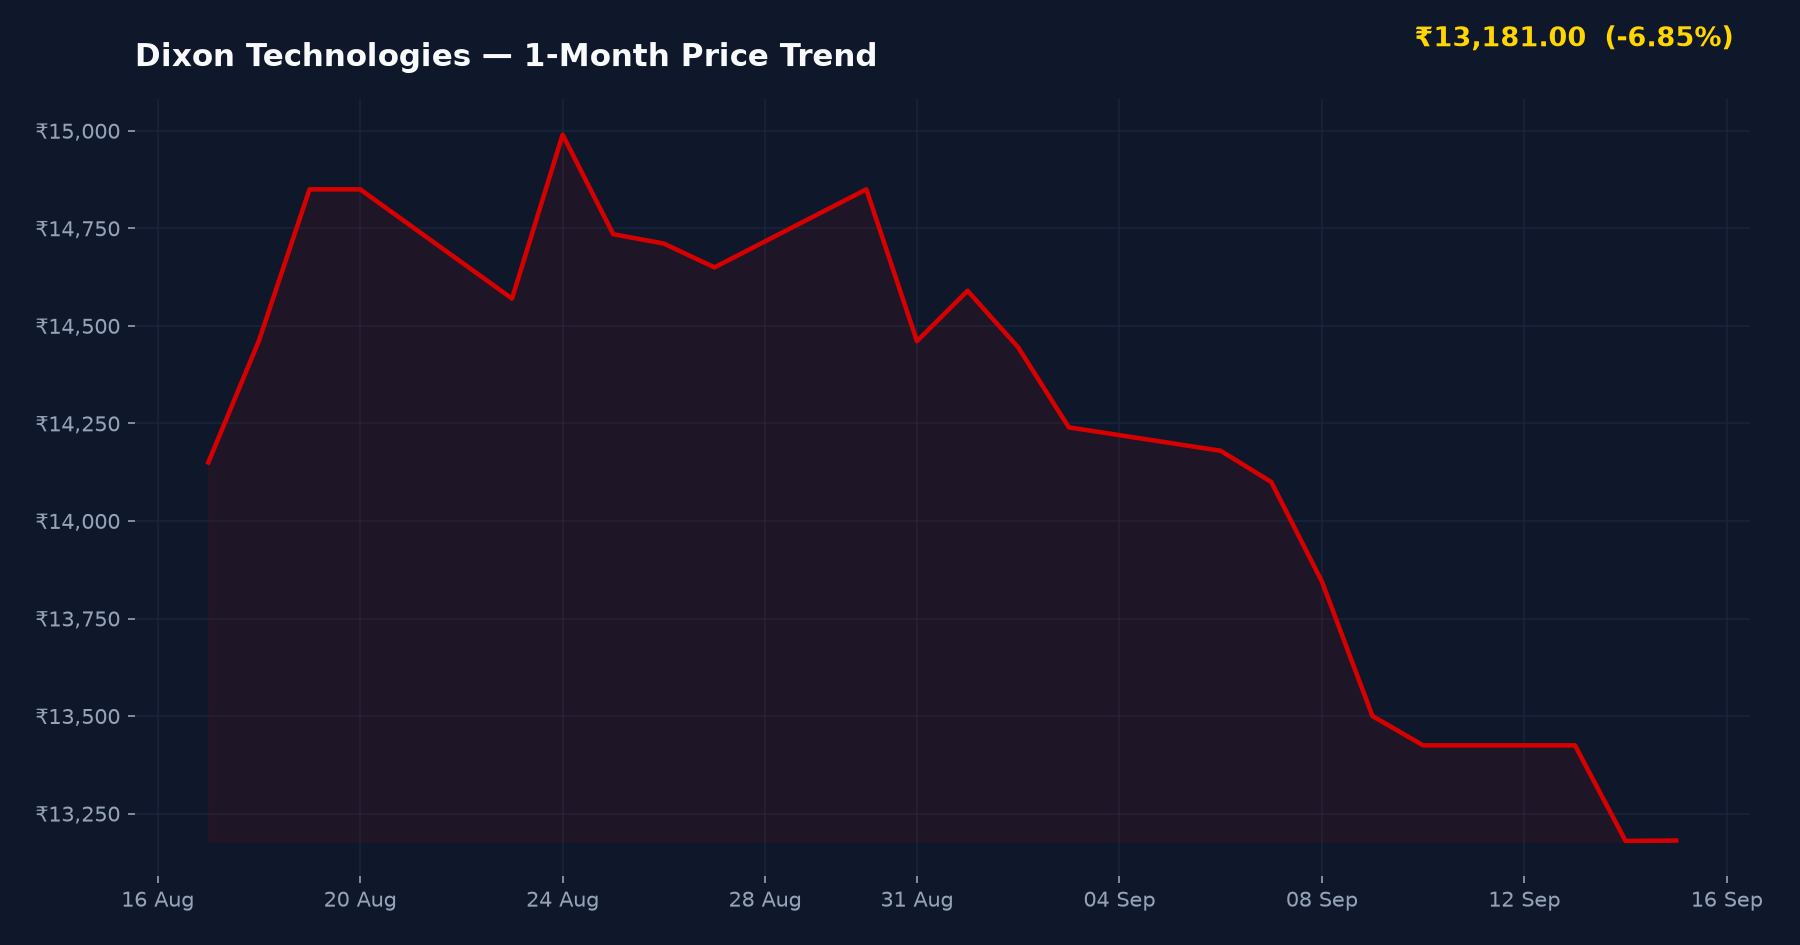
▼ ₹285.00 (-2.14%)
Day Range: ₹13,005.00 – ₹13,383.00
52W Range: ₹9,600.00 – ₹18,471.00
● Real-Time Feed
Key Corporate Milestones & Regulatory Timeline
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| PLI Scheme Expansion Review | September 15, 2026 |
| BSE Regulatory Filing Update | September 18, 2026 |
| Intraday Operational Volume Print | September 19, 2026 |
Financial Parameters & Operational Metrics
| Financial Metric | Reported Value / Status |
|---|---|
| Primary Sector Focus | Electronics Manufacturing Services (EMS) |
| Government Scheme Participation | Smartphone PLI Scheme |
| Backward Integration Depth | PCBs, Displays & Plastic Moulding |
| Listing Exchanges | BSE & NSE India |
In-Depth Analysis: Strategic Scale and Margin Expansion
According to fundamental metrics tracked on Screener.in and Trendlyne, Dixon Technologies has cemented its position as a primary beneficiary of global electronics supply chain diversification toward India. Brokerage insights compiled by Motilal Oswal and ICICIdirect highlight that the company’s continuous volume expansion in mobile manufacturing is no longer driven solely by assembly arbitrage, but by deep backward integration.
PLI Execution and Global Partnerships
The company’s strategic manufacturing tie-ups with global heavyweights—including Xiaomi, Motorola, and Google Pixel—have fueled exponential quarterly revenue growth. Filings submitted to BSE and NSE India confirm that capacity utilization across its primary plants has scaled steadily through the first half of fiscal 2027.
Backward Integration and Margin Resilience
Retail discussions across Reddit r/IndianStockMarket and ValuePickr Forum frequently emphasize Dixon’s aggressive push into precision plastic moulding, printed circuit board (PCB) assemblies, and display modules. This structural vertical integration successfully buffers operating margins against global component price volatility.
Peer Valuation Comparison
| Company / Peer Name | P/E Ratio | Market Cap / Scale | Key Note |
|---|---|---|---|
| Dixon Technologies | Premium | Large Cap EMS | Market leader in mobile and consumer electronics PLI. |
| Amber Enterprises | High | Mid Cap EMS | Strong AC component and ODM footprint. |
| Kaynes Technology | High | Mid Cap EMS | Specialized industrial and automotive electronics. |
Peer valuation data sourced from Screener.in and Trendlyne
Bull vs. Bear Investor Framework
Growth Catalysts (Bull Case):
- Sustained volume expansion supported by active government PLI disbursements.
- Deepening localization and backward integration, boosting operating margins.
- Expanding client roster featuring tier-one global smartphone brands.
Downside Risks (Bear Case):
- Demanding valuation multiples leaving limited room for execution slippage.
- Vulnerability to global semiconductor shortages and raw material price swings.
- Intense domestic competition within the electronic manufacturing services sector.
Investment Verdict & Analytical Summary
Suitable For: Long-term structural equity investors
Risk Level: Medium-High — Elevated valuations require uninterrupted earnings compounding.
Key Watch Point: Quarterly margin sustainability and execution speed on component backward integration.
Frequently Asked Questions
Should investors evaluate Dixon Technologies shares based on current valuations?
Dixon Technologies trades at elevated forward P/E multiples reflecting aggressive growth expectations under the PLI scheme. Long-term investors must weigh structural manufacturing tailwinds against stretched valuation benchmarks.
What drives the margin expansion narrative for Dixon Technologies?
Margin expansion is primarily propelled by backward integration into high-value components like PCB assemblies and display modules, reducing import dependency and improving per-unit realizations.
What are the primary operational risks facing the company?
Key risks include potential supply chain bottlenecks for critical semiconductor components, margin pressures from competitive bidding, and regulatory modifications to government incentive schemes.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, Moneycontrol, Screener.in, Motilal Oswal broker research, Trendlyne.