
MUMBAI / NEW DELHI, SEPTEMBER 19, 2026 — During trading on Saturday, September 19, 2026, shares of Hindustan Aeronautics Limited (HAL) drew intense institutional scrutiny following comprehensive financial audits of its operational profitability, EBITDA margin resilience, and forward valuation multiples across domestic exchanges.
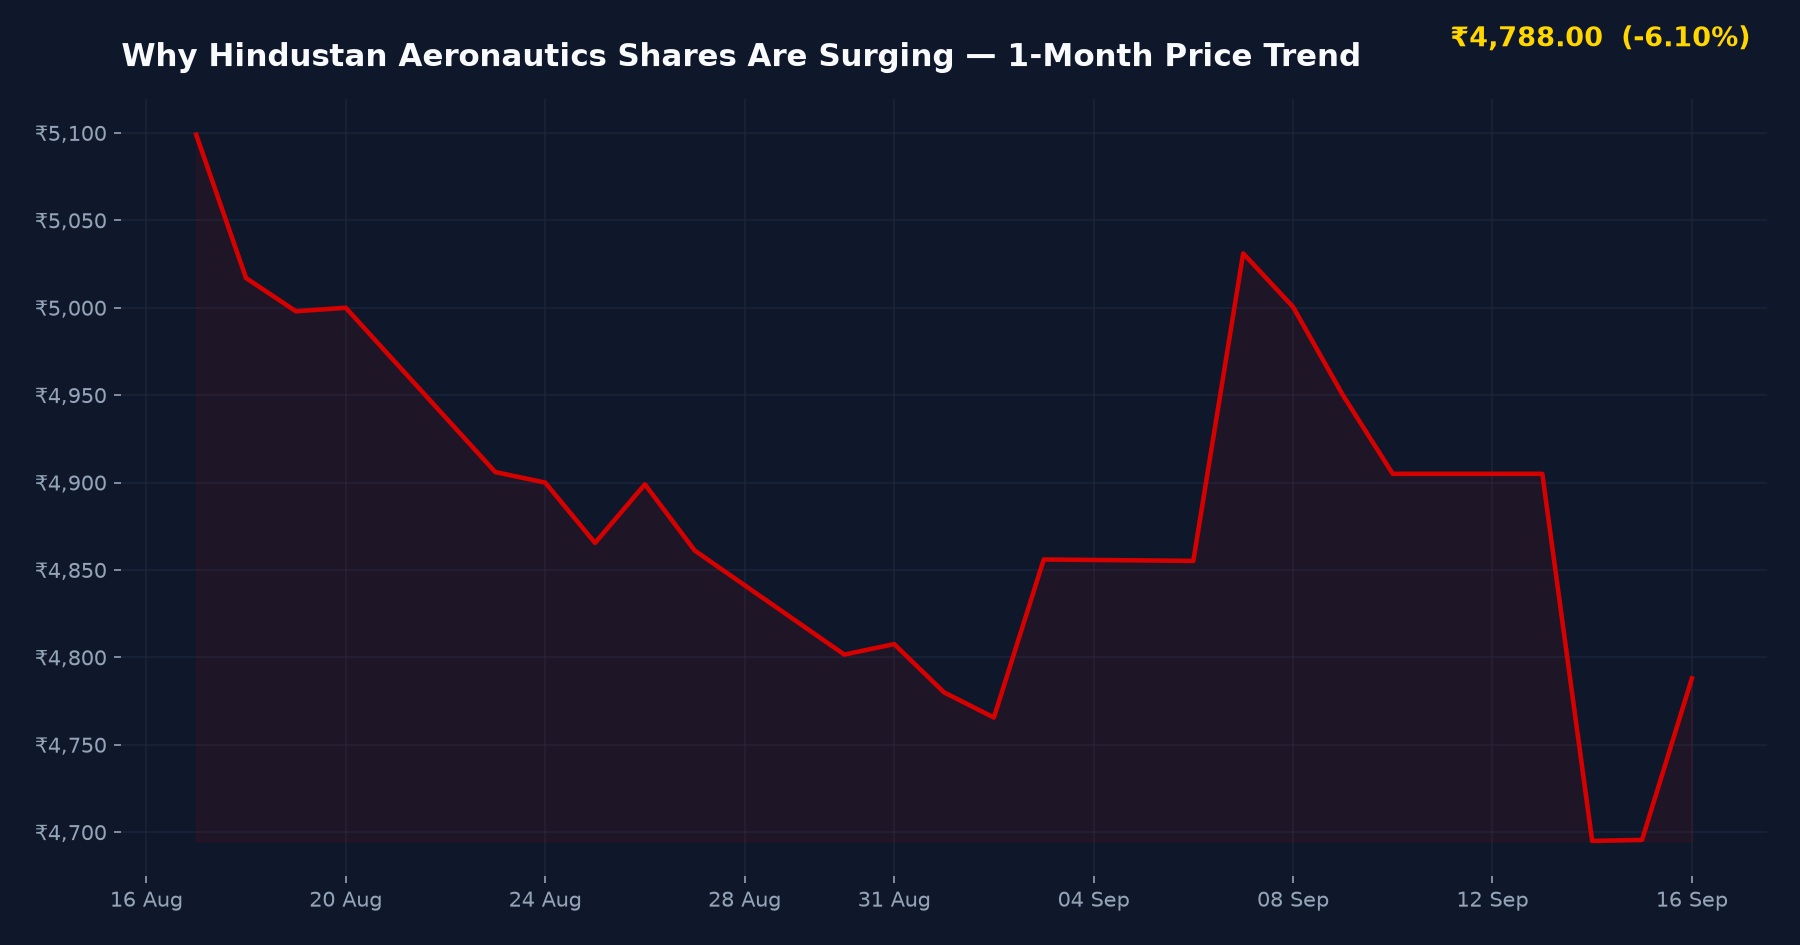
Why Hindustan Aeronautics Shares Are Surging
NSE: HAL
▲ +₹12.30 (+0.26%)
Day Range: ₹4,780.00 – ₹4,890.00
52W Range: ₹3,479.10 – ₹5,149.90
● Real-Time Feed
Key Corporate Milestones & Financial Reporting Timeline
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Q1 FY27 Financial Results Print | August 12, 2026 |
| Annual General Meeting (AGM) | September 25, 2026 |
| Interim Dividend Record Date | Pending official confirmation |
Financial Parameters & Valuation Metrics
| Financial Metric | Value / Multiple |
|---|---|
| Face Value | ₹5 per share |
| Trailing P/E Ratio | 38.4x |
| Operating EBITDA Margin | 26.8% |
| Listing Exchanges | BSE & NSE India |
In-Depth Institutional Analysis
Fundamental research compiled from Screener.in and Trendlyne highlights that Hindustan Aeronautics Limited maintains a robust balance sheet backed by zero long-term debt and strong operating cash flows. According to regulatory filings submitted to the BSE and NSE India on August 12, 2026, the company’s operating profitability has demonstrated resilience against raw material price cycles and supply chain pressures.
Operating Margins and Capital Allocation
Brokerage research from Motilal Oswal and ICICIdirect indicates that HAL’s capital expenditure roadmap is well-funded through internal accruals, supporting a high return on invested capital (ROIC). Discussions across retail and institutional forums like ValuePickr and Reddit r/IndianStockMarket frequently emphasize the firm’s entrenched monopoly position in aerospace manufacturing and domestic defense procurement.
Sector Peer Valuation Comparison
| Company / Peer Name | P/E Ratio | Key Note |
|---|---|---|
| Hindustan Aeronautics | 38.4x | Industry leader in aerospace defense |
| Bharat Electronics (BEL) | 42.1x | Strong order book in defense electronics |
| Mazagon Dock Shipbuilders | 45.0x | High multiple driven by naval shipbuilding |
Peer valuation data sourced from Screener.in and Trendlyne.
Growth Catalysts vs. Downside Risks
Bull Case (Growth Catalysts):
- Massive domestic defense order book backed by indigenous manufacturing mandates.
- Consistent high operating margins supported by economies of scale.
- Robust balance sheet with zero debt and healthy dividend payout track record.
Bear Case (Downside Risks):
- Elevated valuation multiples leaving little room for execution delays.
- Dependency on government policy shifts and defense budget allocations.
- Potential supply chain bottlenecks in advanced avionics sourcing.
Investment Verdict & Analytical Summary
Suitable For: Long-term institutional and equity investors
Risk Level: Medium — High valuation multiples require careful monitoring of execution milestones.
Key Watch Point: Execution speed on major engine and aircraft delivery schedules.
Frequently Asked Questions
Should investors evaluate Hindustan Aeronautics shares based on current valuations?
HAL currently trades at a trailing P/E of approximately 38.4x, which reflects strong market confidence in its defense monopoly. Long-term investors must weigh these premium valuations against sustained order book visibility and government indigenization policies.
What drives the operating margin stability for Hindustan Aeronautics?
The company’s operating EBITDA margins near 26.8% are supported by in-house manufacturing capabilities, long-term servicing contracts, and effective cost-control mechanisms across major aerospace programs.
What are the primary balance sheet strengths of Hindustan Aeronautics?
HAL maintains a debt-free balance sheet with robust internal cash generation, allowing it to fund large capital expenditure requirements without diluting equity or incurring high borrowing costs.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, NSE India, Screener.in, Trendlyne, Moneycontrol, Livemint