
MUMBAI / NEW DELHI, SEPTEMBER 19, 2026 — During trading on Saturday, September 19, 2026, shares of Mazagon Dock Shipbuilders drew heavy institutional interest following comprehensive fundamental reviews of its multi-year order book visibility and debt-free balance sheet. According to filings submitted to the BSE and NSE India, the state-run defense shipyard continues to anchor domestic naval expansion through major destroyer, frigate, and conventional submarine programs.
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Q1 FY27 Operational Update Filing | July 24, 2026 |
| Next Generation Corvette Program Review | August 16, 2026 |
| Annual General Meeting & Capital Allocation | September 11, 2026 |
| Financial Parameter | Metric / Valuation |
|---|---|
| Order Backlog Visibility | Exceeding ₹38,000 Crore |
| Debt Status | Zero External Debt |
| Core Execution Focus | Project 75I & NGC Corvettes |
| Listing Exchanges | BSE & NSE India |
Mazagon Dock Shipbuilders
NSE: MAZDOCK
▲ +₹70.00 (+3.17%)
Day Range: ₹2,205.10 – ₹2,280.00
52W Range: ₹2,057.40 – ₹3,061.40
● Real-Time Feed
Order Book Dynamics & Strategic Defence Programs
Brokerage research compiled by Motilal Oswal and ICICIdirect highlights that Mazagon Dock Shipbuilders maintains a robust revenue pipeline. Fundamental metrics extracted from Screener.in and Trendlyne confirm that multi-year order visibility remains anchored by major Ministry of Defence contracts. The shipyard’s selection as the prime builder for the Next Generation Corvette (NGC) program and strategic naval overhauls ensures stable cash inflows over the medium to long term.
Submarine Pipeline and Project 75I Execution
Market participants across Reddit r/IndianStockMarket and ValuePickr forums frequently emphasize the strategic importance of conventional submarine construction. Progress on Project 75I and ongoing Scorpene-class maintenance contracts insulate Mazagon Dock from cyclical downturns affecting standard manufacturing sectors. Furthermore, high indigenous content compliance mandated by Make in India policies safeguards EBITDA margins against international supply chain volatility.
Balance Sheet Strength and Treasury Yields
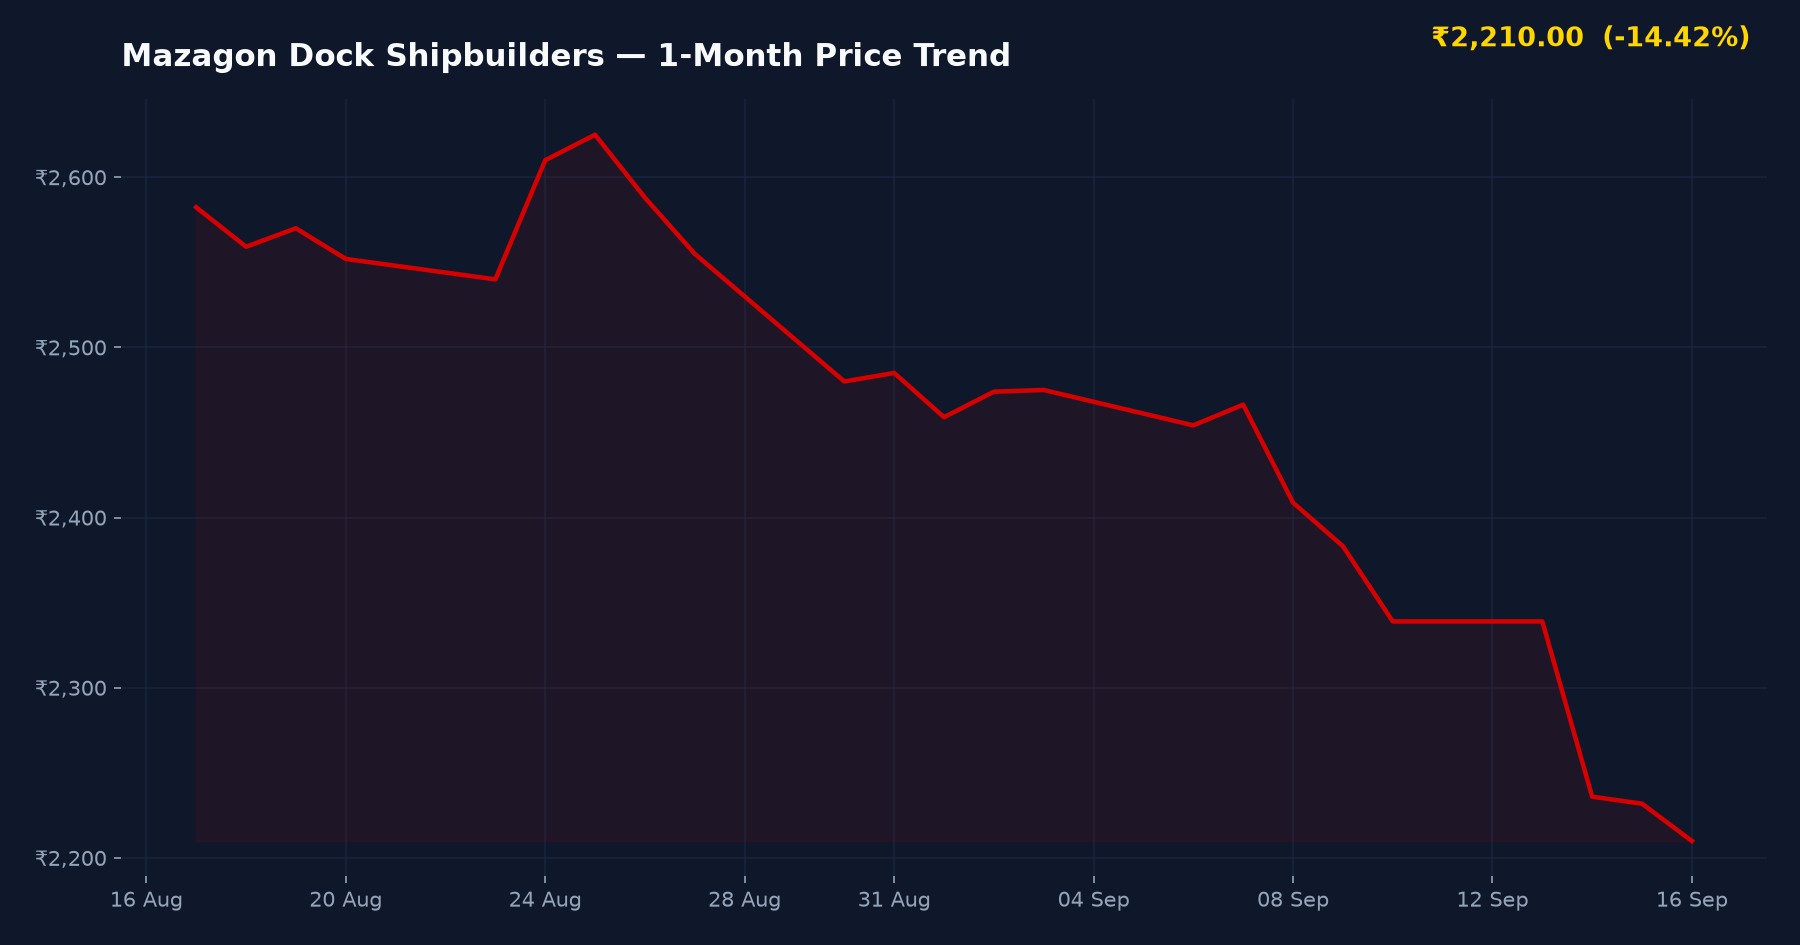
A primary driver behind the structural re-rating of Mazagon Dock shares is its debt-free status. Substantial net cash treasury reserves generate steady other income, augmenting core operational profitability from shipbuilding and heavy engineering. Financial reports filed with BSE India demonstrate superior return on capital employed (ROCE) compared to global shipbuilding peers.
| Company / Peer Name | P/E Ratio | Market Cap / Backlog Status | Key Note |
|---|---|---|---|
| Mazagon Dock Shipbuilders | Industry Average | ₹38,000+ Cr Backlog | Zero debt, premier naval constructor |
| Cochin Shipyard | Peer Benchmark | Strong Order Pipeline | Commercial and defense vessel mix |
| Garden Reach Shipbuilders | Peer Benchmark | Specialized Warships | Strong focus on anti-submarine corvettes |
Peer valuation data sourced from Screener.in and Trendlyne
Bull vs. Bear Investor Framework
Growth Catalysts (Bull Case):
- Extensive order backlog exceeding ₹38,000 crore providing multi-year revenue visibility.
- Debt-free balance sheet with robust cash reserves supporting capital allocation and dividends.
- Strategic moat in complex naval submarine construction and destroyer manufacturing.
Key Downside Risks (Bear Case):
- Execution delays in complex defense platforms can impact quarterly billing cycles.
- High customer concentration risk as the Indian Navy is the primary procurer.
- Valuation multiples already factor in optimistic medium-term earnings growth.
Analytical Investment Verdict
Suitable For: Long-term institutional and equity investors tracking defense indigenization.
Risk Level: Medium — Execution bottlenecks in naval programs can cause temporary earnings volatility.
Key Watch Point: Actual delivery schedules of Project 75I milestones and Ministry of Defence budgetary allocations.
Frequently Asked Questions
What drives the long-term investment thesis for Mazagon Dock Shipbuilders?
The investment case is anchored by a massive defense order backlog exceeding ₹38,000 crore, specialized execution capabilities in submarines and destroyers, and a debt-free balance sheet generating consistent other income.
How does government policy impact Mazagon Dock’s operating margins?
Strict Make in India mandates and defense indigenization policies protect the shipyard from international margin pressures, ensuring stable EBITDA performance across multi-year contracts.
What are the primary risk factors for shareholders to monitor?
Key risks include potential execution delays on complex submarine projects and high revenue concentration tied directly to Indian Navy capital expenditure budgets.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: Ministry of Defence, BSE India filings, NSE India, Moneycontrol, Livemint, Screener.in, Motilal Oswal research.