
MUMBAI / NEW DELHI, SEPTEMBER 22, 2026 — During trading on Tuesday, market analysts at Moneycontrol and leading financial institutions dissected the multi-year trajectory of the Nifty 50, revealing that thirteen specific index constituents significantly suppressed overall benchmark returns over a five-year evaluation window.
NIFTY 50
INDEX
▲ +₹67.90 (+0.29%)
Day Range: ₹23,314.80 – ₹23,466.80
52W Range: ₹22,182.55 – ₹26,373.20
● Real-Time Feed
Key Milestone Timeline
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Technical Review & Trend Reversal Level Analysis | September 21, 2026 |
| Trade Setup & Market Open Assessment | September 22, 2026 |
| Index Constituent & Mutual Fund Performance Audit | Pending official exchange rebalancing |
Index Composition and Performance Drag Analysis
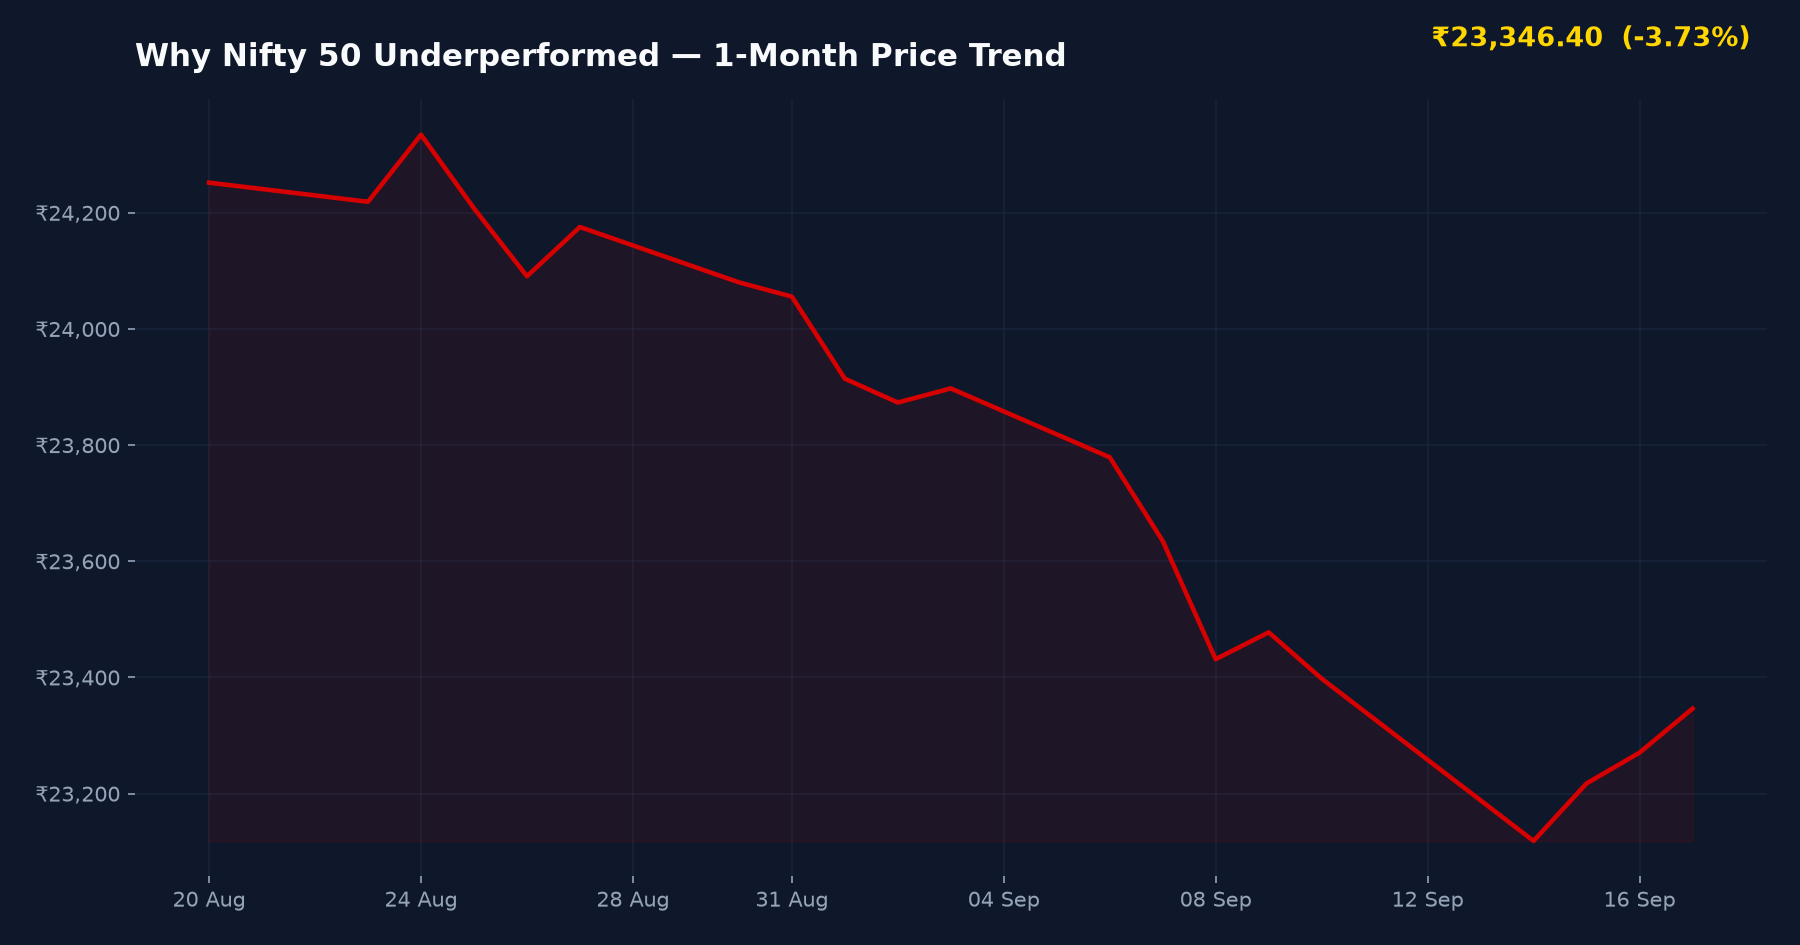
According to fundamental reviews compiled across market intelligence platforms like Moneycontrol and Livemint, the Nifty 50 index achieved overall gains during the evaluated five-year timeframe, yet its absolute performance was severely capped by 13 persistent laggards. These specific equities posted negative individual returns, dragging down the aggregate index yield.
Had these underperforming stocks been excluded from the basket, the Nifty 50 would have delivered significantly higher returns for passive investors. This structural drag created a unique window for actively managed mutual funds, which leveraged reduced exposure to these exact laggards to outperform the headline index.
Active vs. Passive Fund Dynamics
The outperformance of active mutual funds over passive index funds during this period underscores the limitation of market-cap-weighted indices in volatile macro environments. Brokerage insights and research roundups emphasize that active fund managers successfully navigated sector rotation by underweighting or completely avoiding the 13 underperforming components.
Bull vs. Bear Catalysts
Growth Catalysts (Bull Case):
- Active fund strategies successfully mitigating index drag through stock-picking agility.
- Robust corporate earnings growth across top-tier banking and IT heavyweights balancing out laggards.
- Continuous retail SIP inflows providing strong institutional support to the broader market.
Downside Risks (Bear Case):
- Concentration risk inherent in cap-weighted indices where a handful of laggards can suppress overall yields.
- Macroeconomic headwinds impacting cyclical sectors represented within the index.
- Potential valuation compression if earnings growth fails to justify current multiple expansions.
Investment Verdict & Analytical Summary
Suitable For: Both active mutual fund investors and long-term index allocators
Risk Level: Medium — reflects broad equity market volatility and index concentration risks
Key Watch Point: Ongoing quarterly earnings divergence between index heavyweights and laggard stocks
Frequently Asked Questions
Why did the Nifty 50 underperform relative to active mutual funds over the last 5 years?
The Nifty 50 was weighed down by 13 specific constituent stocks that delivered negative returns over the period. Active mutual funds outperformed by maintaining lower or zero exposure to these laggards, thereby capturing superior alpha.
Does index investing still make sense given the drag caused by laggard stocks?
Yes, index investing remains a cost-effective strategy for long-term wealth creation, though investors seeking to bypass single-stock drag often supplement core index holdings with actively managed funds or diversified asset classes like REITs.
How can retail investors identify underperforming index constituents?
Investors can track quarterly financial results, fundamental screener data, and sector performance reports published by financial portals like Moneycontrol and Screener.in to monitor stock-level value destruction.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: Moneycontrol, Livemint, Economic Times, BSE India filings