
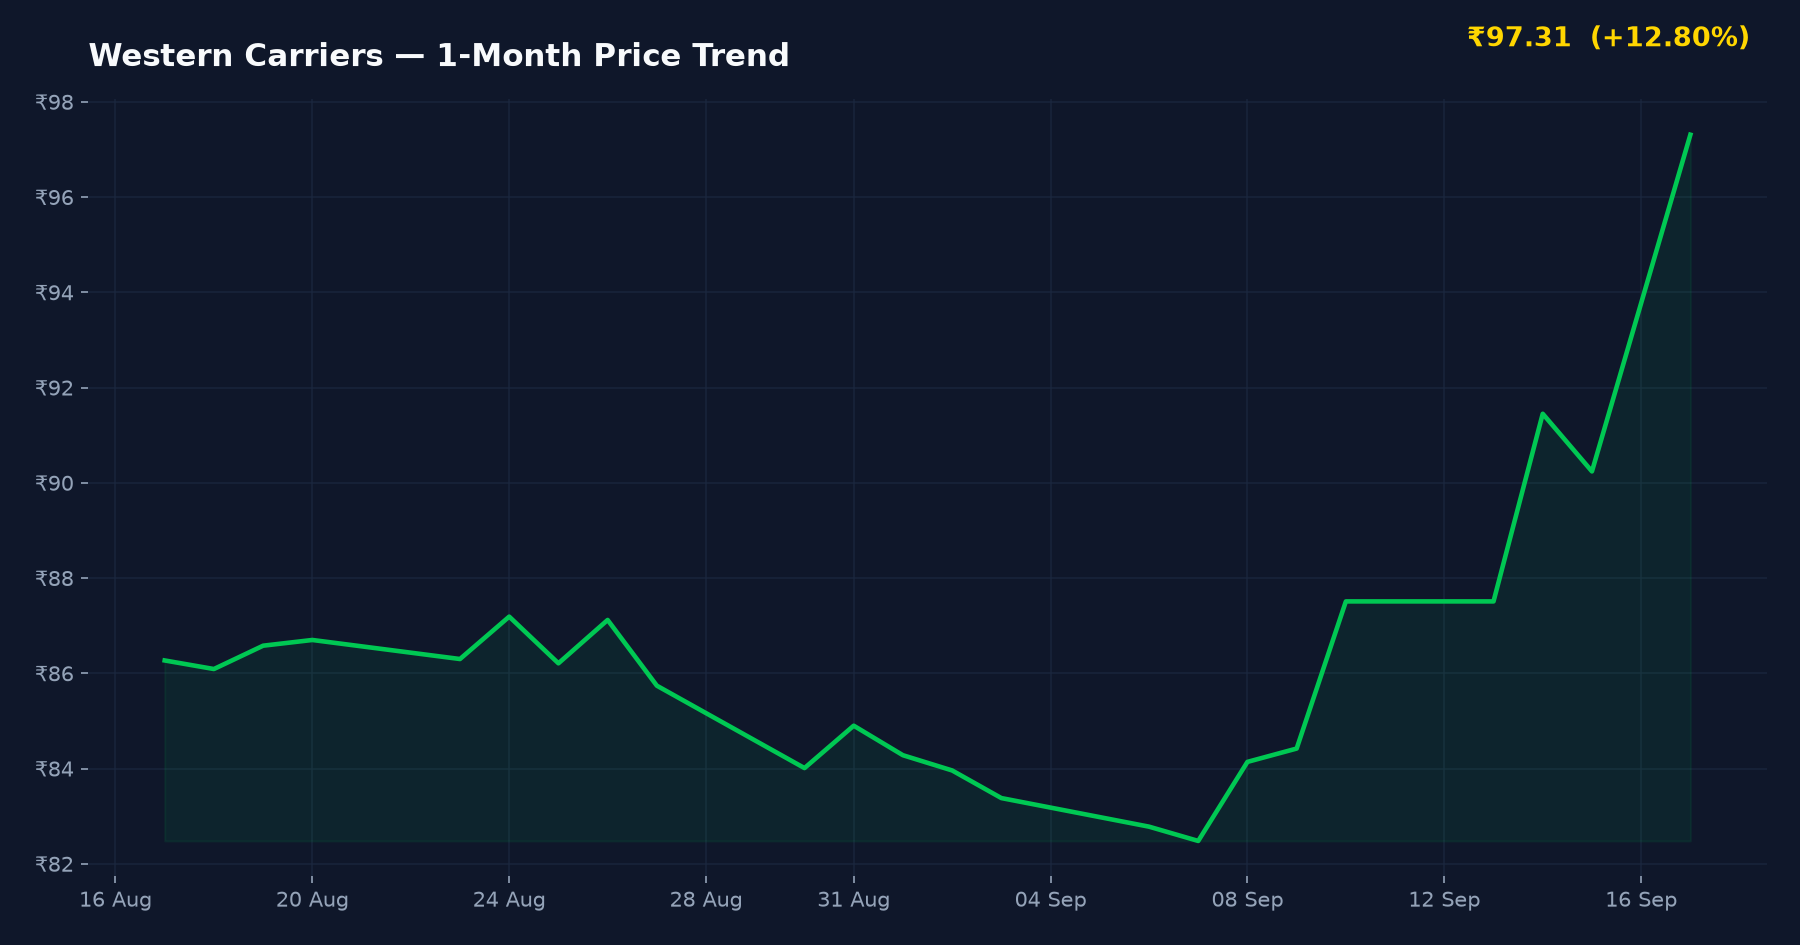
MUMBAI / NEW DELHI, SEPTEMBER 18, 2026 — During morning trade on Friday, September 18, 2026, shares of Western Carriers (India) remained in focus as analysts conducted a post-listing audit of the company’s operational health. Following its recent debut on the bourses, the company is aggressively deploying capital to prepay high-interest commercial vehicle loans and expand its specialized container fleet to service blue-chip clients like Tata Steel and JSW Steel.
Western Carriers
NSE: WCIL
▲ +₹2.10 (+2.21%)
Day Range: ₹95.00 – ₹99.99
52W Range: ₹77.02 – ₹147.29
● Real-Time Feed
Key Post-Listing Timeline & Milestones

| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Post-Listing Audit Review | September 18, 2026 |
| Fleet Expansion Commencement | Pending Q3 FY27 Update |
Operational Metrics & Financial Health
| Financial Metric | Value / Status |
|---|---|
| Operating Profit Margin (OPM) | 8% – 10% |
| Primary Client Concentration | Metals & Mining |
| Utilization of IPO Proceeds | Debt Prepayment |
| Listing Exchanges | BSE & NSE |
In-Depth Analysis: Multi-Modal Integration & Margin Sustainability
According to fundamental research from Screener.in and Trendlyne, Western Carriers operates an asset-light model that differentiates itself through dedicated railway siding access. This infrastructure allows the company to seamlessly transition cargo between rail and road, significantly reducing turnaround times for heavy industrial clients.
Debt Reduction as a Margin Catalyst
Regulatory filings submitted to BSE India confirm that a substantial portion of the fresh issue proceeds was earmarked for the prepayment of commercial vehicle loans. Brokerage insights from Motilal Oswal suggest that this deleveraging will likely lead to an immediate expansion in net profit margins (PAT) as interest outgo decreases. The company’s ability to maintain 8-10% operating margins in a competitive logistics landscape is viewed as a sign of strong pricing power with its core mining clientele.
Peer Comparison: Valuation Context
| Company Name | P/E Ratio | Key Note |
|---|---|---|
| Western Carriers | Peer-Linked | Focus on Rail-Road integration |
| Container Corp (CONCOR) | 38.5 | Public sector giant |
| Gateway Distriparks | 18.2 | Private container player |
Peer valuation data sourced from Screener.in and Trendlyne.
Balanced Investor Framework
Bull Case Catalysts
- Strong relationship with industrial giants like Vedanta and JSW ensures long-term revenue visibility.
- Asset-light strategy reduces capital expenditure pressure compared to traditional fleet owners.
Bear Case Risks
- High dependence on the metals and mining sector makes the company vulnerable to commodity price cycles.
- Fuel price volatility and railway freight rate hikes can compress operating margins.
Investment Verdict
Suitable For: Long-term HNI and Institutional Investors.
Risk Level: Medium — Driven by sector concentration in mining and metals.
Key Watch Point: Monitor the quarterly reduction in finance costs following the IPO debt repayment.
Frequently Asked Questions
Should investors hold Western Carriers shares based on valuations?
Investors should evaluate Western Carriers based on its ability to scale its multi-modal integration. If the company successfully transitions to a lower-debt balance sheet, its valuation multiples may align closer to premium private logistics players.
What is the significance of the company’s 10% operating margins?
A 10% OPM is considered healthy for the logistics sector, especially for a company utilizing rail-road combinations. It indicates efficient container turnaround times and strong negotiation leverage with railway authorities.
What are the primary risks for Western Carriers?
The primary risks include high client concentration in the steel and mining industries and potential working capital stretches due to the long credit cycles typical of heavy industrial logistics.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents (DRHP/RHP) thoroughly before committing capital. Grey Market Premium (GMP) figures are unofficial, unregulated street estimates. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, Moneycontrol, Screener.in, Livemint, Motilal Oswal Research.