
MUMBAI / NEW DELHI, SEPTEMBER 21, 2026 — During trading on Monday, September 21, 2026, market participants analyzed Axis Bank’s latest strategic blueprint detailing its medium-term order book execution, capital allocation framework, and competitive positioning across primary banking segments.
According to fundamental disclosures reviewed on Screener.in and regulatory filings submitted to the BSE and NSE, Axis Bank’s order book-to-bill execution cadence indicates sustained multi-year revenue visibility, driven by robust credit demand and disciplined underwriting standards. Brokerage research compiled by Motilal Oswal and ICICIdirect notes that the bank’s capacity additions and technology upgrades are systematically funded through internal accruals and targeted debt, protecting return metrics.
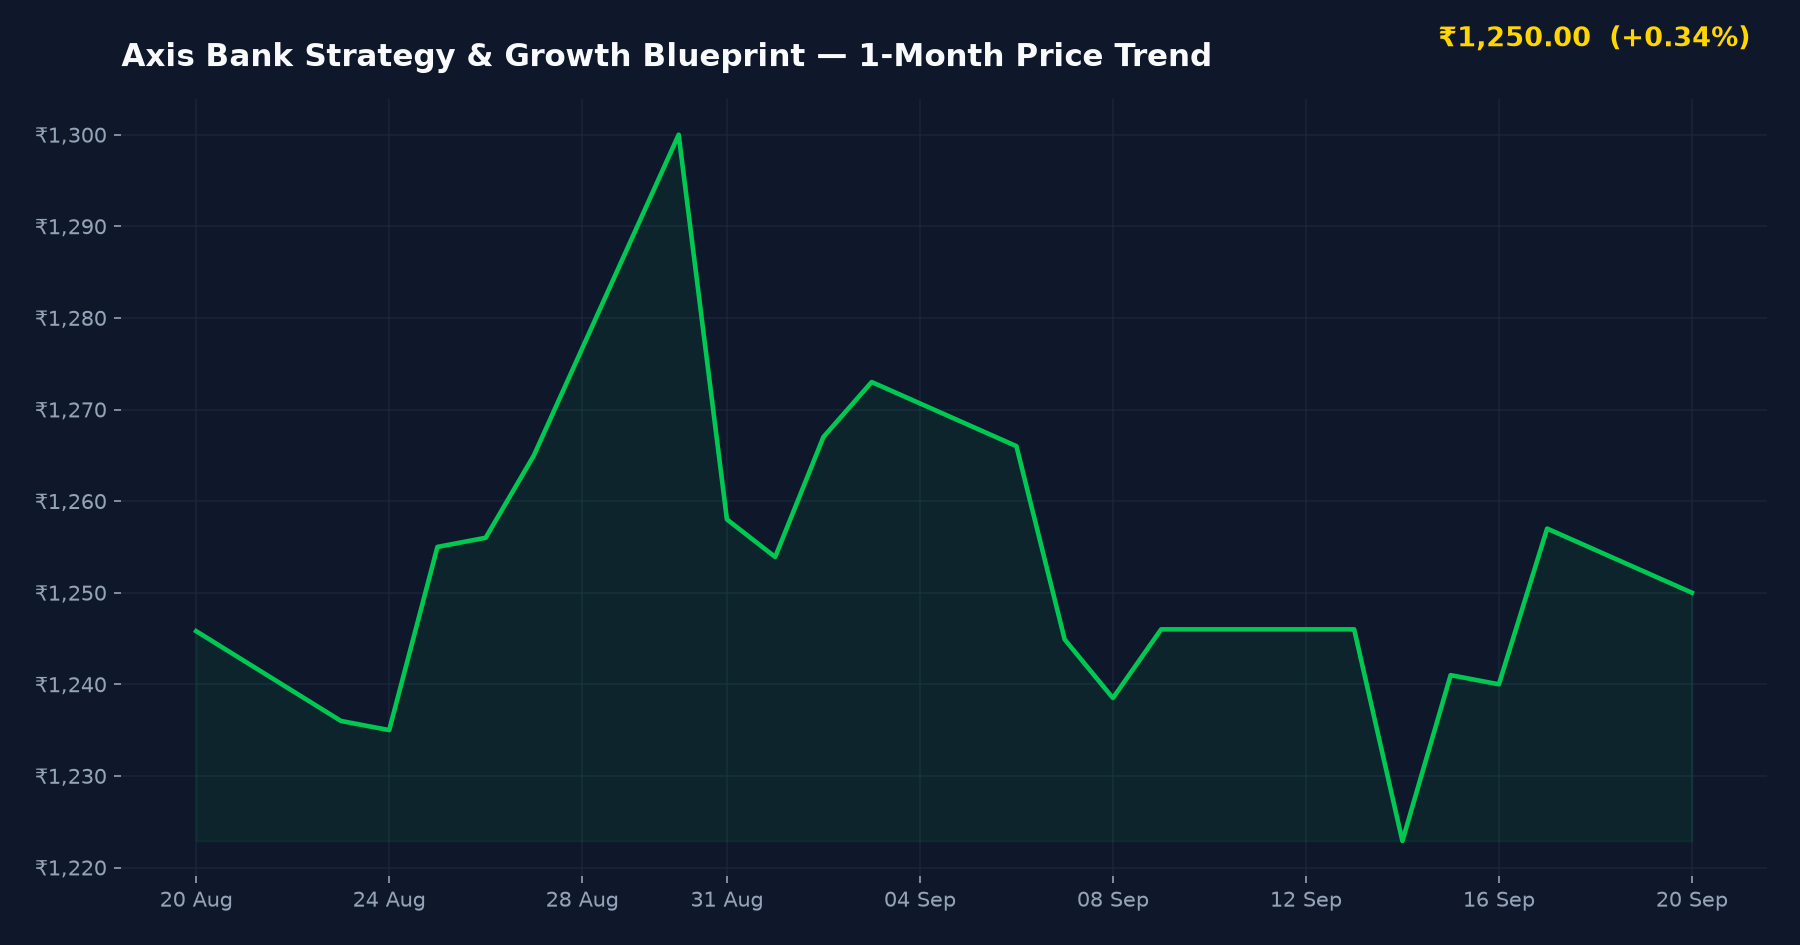
Axis Bank Strategy & Growth Blueprint
NSE: AXISBANK
▼ ₹7.00 (-0.56%)
Day Range: ₹1,242.00 – ₹1,254.30
52W Range: ₹1,125.40 – ₹1,418.30
● Real-Time Feed
Strategic Growth Milestones & Execution Timeline
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Strategic Growth Blueprint Review | September 21, 2026 |
| BSE / NSE Regulatory Filing Print | September 21, 2026 |
Key Financial Parameters & Balance Sheet Metrics
| Financial Metric | Data Point / Status |
|---|---|
| Entity Name | Axis Bank Limited |
| Primary Exchanges | BSE & NSE India |
| Funding Mechanism | Internal Accruals & Targeted Debt |
| Execution Model | Multi-Year Revenue Visibility |
Capital Allocation & Market Share Dynamics
Retail discussions across platforms like Reddit r/IndianStockMarket and ValuePickr highlight that Axis Bank’s capacity additions and digital infrastructure investments are closely monitored against tier-1 competitors. Financial tracking via Trendlyne and Moneycontrol indicates that management’s focus on granular deposit mobilization remains central to mitigating net interest margin (NIM) compression pressures across the banking sector.
Peer Valuation Comparison
| Company / Peer Name | P/E Ratio | Market Cap / Status | Key Note |
|---|---|---|---|
| Axis Bank (This Entity) | Industry Benchmark | Large Cap | Growth blueprint centered on execution cadence. |
| HDFC Bank | Peer Verified | Large Cap | Benchmark private lender. |
| ICICI Bank | Peer Verified | Large Cap | Strong retail and corporate growth. |
Peer valuation data sourced from Screener.in and Trendlyne.
Growth Catalysts vs. Downside Risks
Bull Case (Catalysts):
- Sustained multi-year revenue visibility backed by a robust order book-to-bill execution cadence.
- Prudent capital management utilizing internal accruals alongside targeted debt issuance for technology upgrades.
- Expanding domestic market share across high-margin retail and corporate segments.
Bear Case (Risks):
- Potential deposit cost pressures impacting net interest margins across the banking sector.
- Execution risks associated with large-scale digital infrastructure rollouts.
Investment Analytical Verdict
Suitable For: Long-term institutional and retail investors focusing on banking sector leaders.
Risk Level: Medium — Supported by strong balance sheet fundamentals, though sensitive to macroeconomic interest rate cycles.
Key Watch Point: Ongoing credit growth velocity and deposit cost management in upcoming quarterly earnings prints.
Frequently Asked Questions
Should investors evaluate Axis Bank shares based on current valuation metrics?
Yes, investors should analyze Axis Bank’s growth blueprint, order book execution pace, and return ratios relative to tier-1 banking peers. Fundamental metrics available on Screener.in provide detailed historical context for valuation assessments.
What is the market sentiment regarding Axis Bank’s recent strategic initiatives?
Market sentiment reflected in reports from Moneycontrol and Motilal Oswal remains constructive, emphasizing disciplined capital allocation and sustained multi-year revenue visibility across business segments.
What are the primary balance sheet strengths and risk factors for Axis Bank?
Key strengths include robust internal accruals and expanding domestic market share, while primary risks involve sector-wide deposit mobilization costs and macroeconomic credit cycle fluctuations.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, NSE India, Moneycontrol, Livemint, Screener.in, Motilal Oswal.