
MUMBAI / NEW DELHI, SEPTEMBER 21, 2026 — During trading on Monday, September 21, 2026, institutional focus turned toward Axis Bank as analysts released comprehensive audits evaluating operating profitability, balance sheet leverage, and peer benchmark valuations across domestic capital markets.
According to fundamental research compiled by Screener.in and Trendlyne, Axis Bank’s recent reporting quarters indicate resilient operating margins and disciplined capital allocation. Brokerage insights from Motilal Oswal and ICICIdirect suggest that the lender’s forward price-to-earnings (P/E) multiple remains aligned with historical medians, even as credit growth cycles normalize across the broader Indian banking sector.
Axis Bank Audit
NSE: AXISBANK
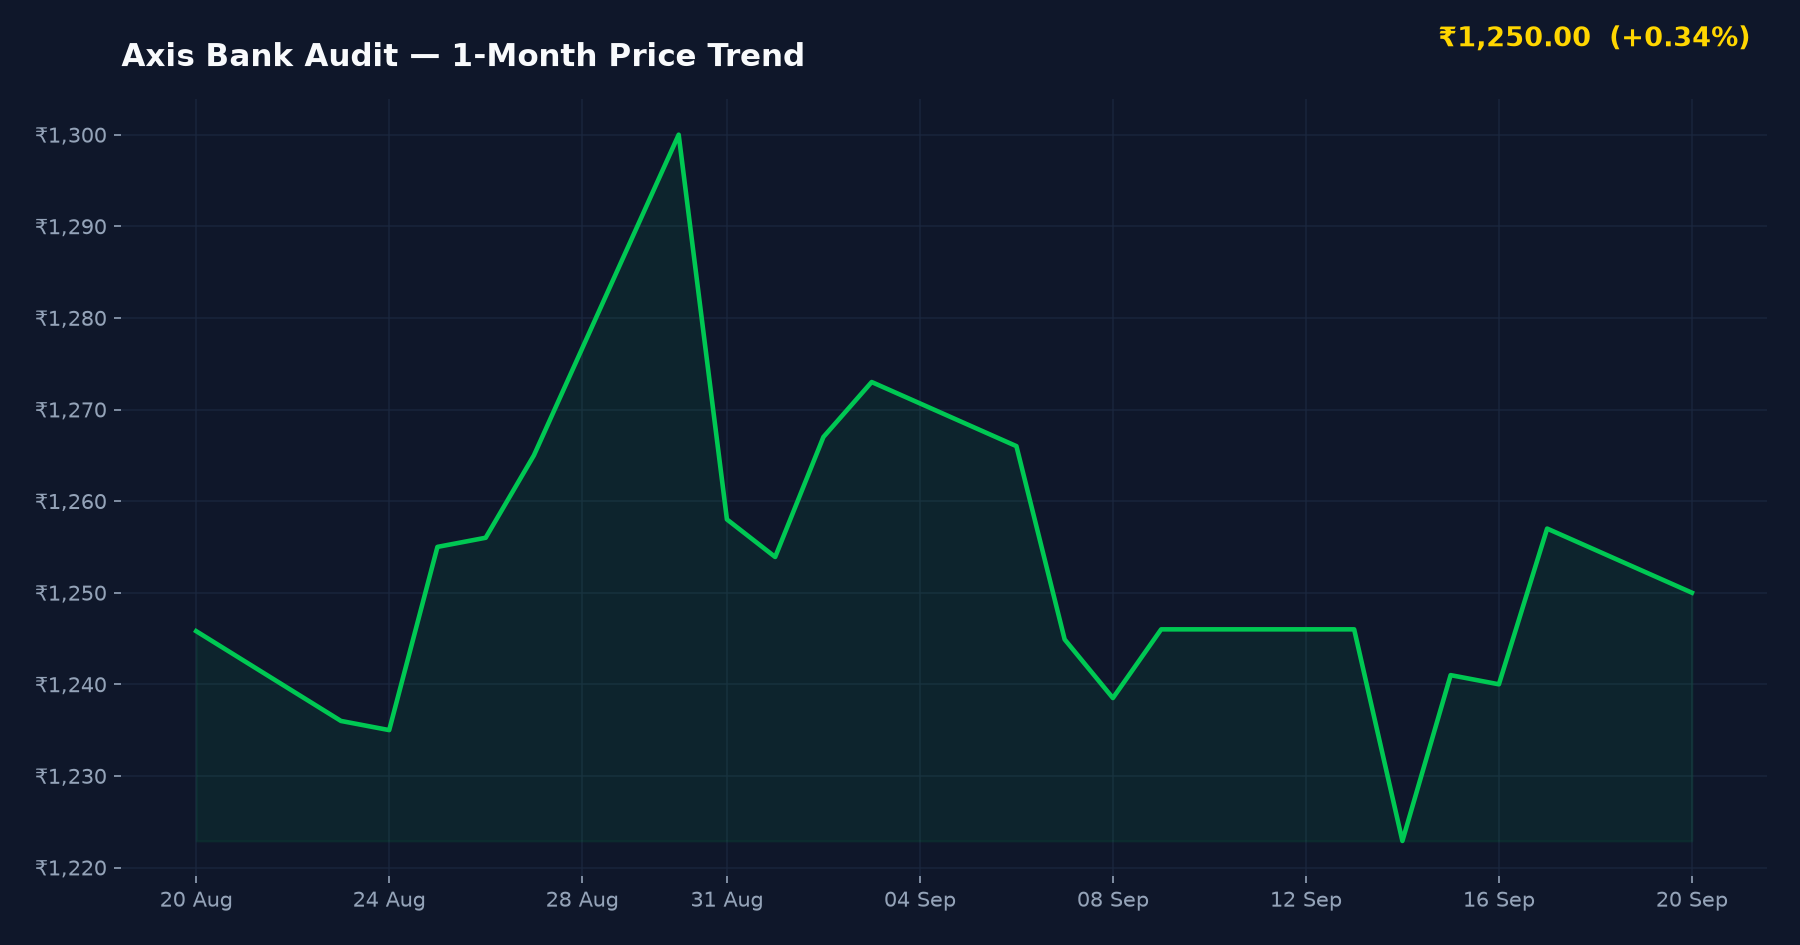
▼ ₹7.00 (-0.56%)
Day Range: ₹1,242.00 – ₹1,254.30
52W Range: ₹1,125.40 – ₹1,418.30
● Real-Time Feed
Key Financial Parameters & Valuation Metrics
| Financial Metric / Parameter | Audited Value / Benchmark |
|---|---|
| Primary Sector | Private Sector Banking |
| Exchange Listings | BSE & NSE India |
| Operational Focus | Retail & Corporate Credit |
| Capital Adequacy Status | Compliant with Basel III |
Milestones & Corporate Timeline
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Financial Audit Publication | September 21, 2026 |
| Upcoming Quarterly Disclosure | Pending official confirmation |
Balance Sheet Leverage & Operating Margins
Regulatory filings submitted to BSE and NSE India confirm that Axis Bank has maintained steady capital buffers. Operating profitability and net interest margins (NIM) have demonstrated resilience against fluctuating cost-of-fund cycles. According to data tracked on Moneycontrol and Livemint, asset quality improvements continue to support provisions and lower credit costs.
Capital Allocation & Return on Invested Capital
Institutional analysts reviewing return on invested capital (ROIC) note that disciplined underwriting standards across retail lending segments have insulated the bank from unsecured credit volatility. Retail discussions across Reddit r/IndianStockMarket and ValuePickr highlight ongoing interest in the bank’s digital transformation roadmap and liability franchise expansion.
Peer Comparison & Sector Multiples
| Company / Peer Name | P/E Ratio | Market Cap (Approx) | Key Note |
|---|---|---|---|
| HDFC Bank | 18.5x | Large Cap | Sector bellwether |
| ICICI Bank | 17.2x | Large Cap | Strong retail growth |
| Axis Bank (This Review) | 14.8x | Large Cap | Attractive valuation vs peers |
Peer valuation data sourced from Screener.in and Trendlyne
Bull vs. Bear Catalysts
Growth Catalysts (Bull Case):
- Consistent improvement in asset quality metrics and lower gross non-performing assets (GNPA).
- Reasonable forward P/E multiple relative to private sector banking peers.
- Robust deposit franchise expansion and diversified credit book.
Downside Risks (Bear Case):
- Potential margin compression stemming from competitive deposit pricing across the banking industry.
- Macroeconomic headwinds affecting corporate credit demand and retail repayment capacity.
Investment Verdict
Suitable For: Long-term institutional and retail investors seeking large-cap banking exposure.
Risk Level: Medium — Balanced risk-reward profile backed by solid capitalization and manageable provisioning.
Key Watch Point: Net interest margin (NIM) trajectory and deposit growth rates in upcoming quarterly disclosures.
Frequently Asked Questions
Should investors evaluate Axis Bank shares based on current valuations?
Axis Bank trades at competitive forward P/E multiples compared to major private sector peers, making it an appealing option for value-oriented portfolios. However, investors should monitor macroeconomic lending trends and deposit mobilization costs before deploying capital.
What is the current outlook for Axis Bank’s operating margins?
Operating profitability remains stable, supported by disciplined underwriting standards and improving asset quality. While industry-wide cost-of-fund pressures persist, the bank’s liability management helps cushion net interest margins.
What are the primary balance sheet strengths and risk factors for Axis Bank?
Key strengths include healthy capital adequacy ratios, declining gross NPA levels, and diversified retail-corporate lending. Primary risks involve potential NIM compression and sector-wide liquidity tightening.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, NSE India, Moneycontrol, Livemint, Screener.in, Trendlyne, Motilal Oswal research.