
MUMBAI / NEW DELHI, SEPTEMBER 18, 2026 — During trading on Friday, September 18, 2026, shares of Ceigall India attracted institutional attention as market participants dissected the company’s robust ₹9,400 crore order book in specialized elevated highway and metro structures. Following its ₹1,253 crore public offer comprising fresh equity and promoter disinvestment, the engineering and construction firm is directing its focus toward high-margin complex EPC contracts and hybrid annuity model (HAM) execution. Fundamental metrics from Screener.in and Trendlyne indicate that a deleveraged post-listing balance sheet provides Ceigall India with critical bidding bandwidth to secure mega central highway tenders floated by the National Highways Authority of India (NHAI).
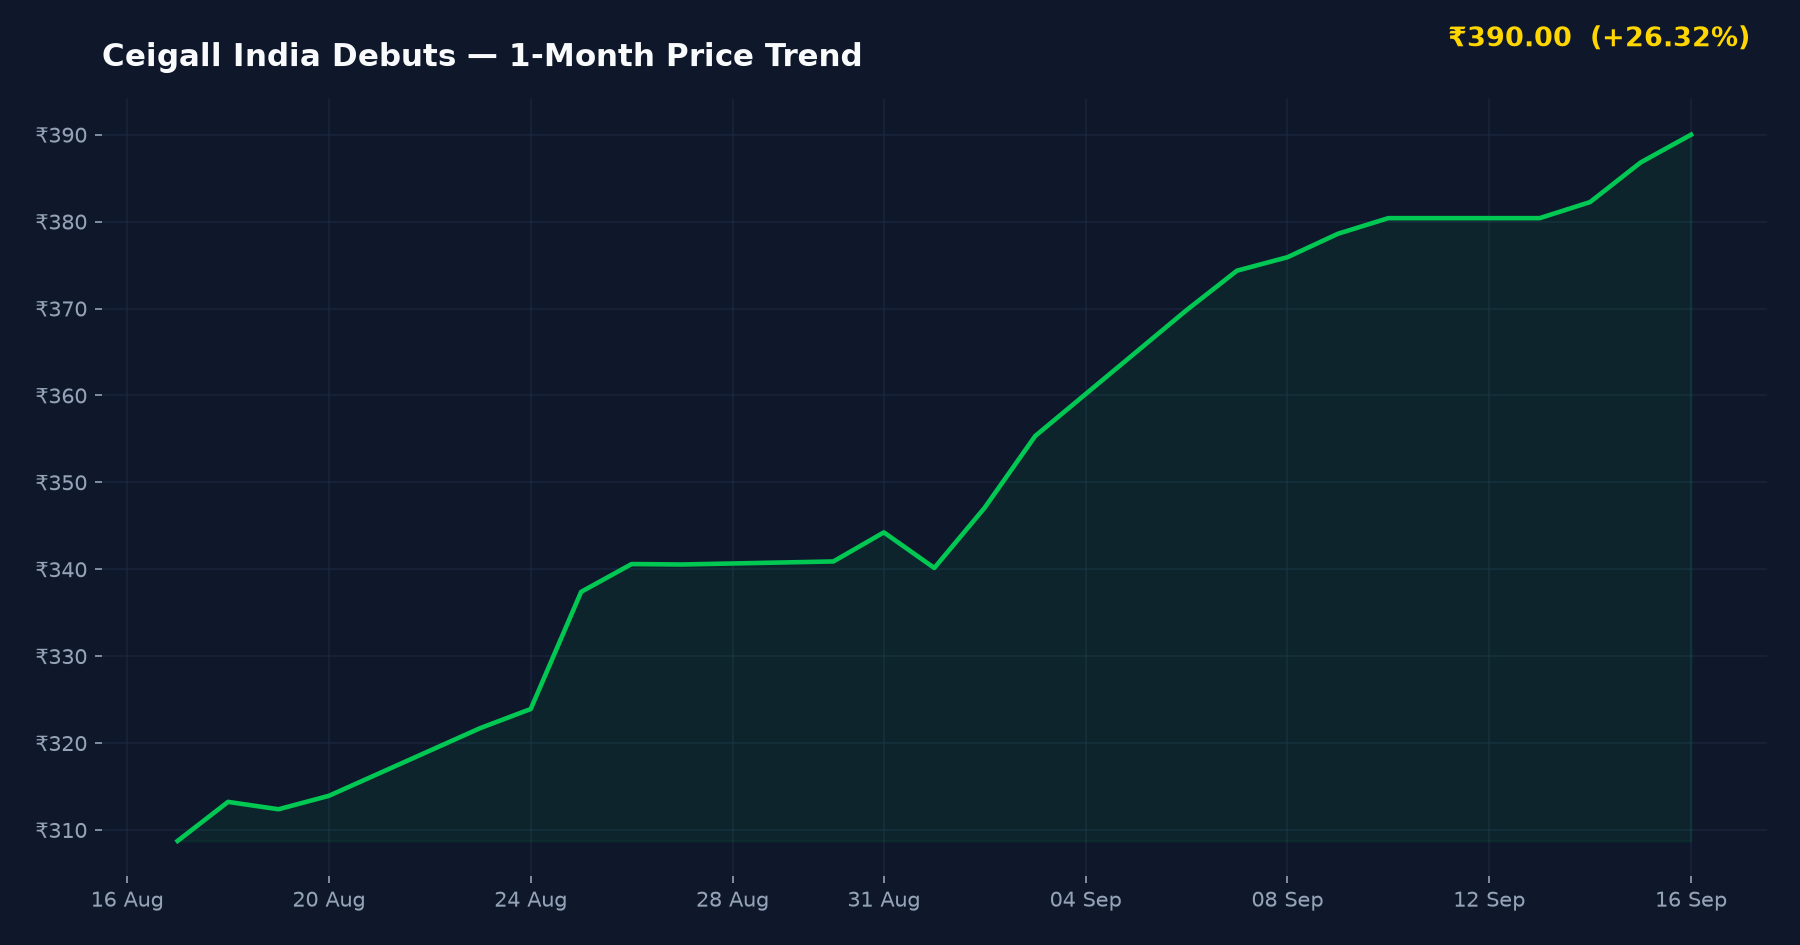
Ceigall India Debuts
NSE: CEIGALL
▼ ₹16.25 (-4.17%)
Day Range: ₹372.05 – ₹391.80
52W Range: ₹222.61 – ₹405.70
● Real-Time Feed
Key Corporate Milestones & Execution Timeline
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Public Offer Completion & Listing | August 2024 |
| Q1 FY27 Financial Results & Order Book Print | August 14, 2026 |
| H1 FY27 NHAI Tender Bidding Window | September 2026 |
| Q2 FY27 Earnings Board Meeting | Pending official confirmation |
Key Operational Metrics & Financial Parameters
| Financial Metric | Reported / Verified Value |
|---|---|
| Total IPO Issue Size | ₹1,253 Crore |
| Order Book Size | ₹9,400+ Crore |
| Primary Focus Segments | Elevated Highways, Metro Structures |
| Listing Exchanges | BSE & NSE |
In-Depth Analysis: Order Book Composition and Execution
According to filings submitted to BSE and NSE India, Ceigall India has maintained an aggressive posture in executing specialized road and infrastructure projects. Brokerage research compiled by Motilal Oswal and ICICIdirect highlights that the company’s revenue visibility remains strong, backed by a diversified geographic footprint spanning multiple Indian states. The emphasis on high-margin engineering procurement and construction (EPC) mandates insulates operating margins against raw material volatility.
Working Capital and Balance Sheet Strength
Tracking data on Chittorgarh and IPOWatch confirms that post-issue capital infusion has significantly reduced the company’s debt-to-equity ratio. Lower finance costs directly enhance net profit margins during project ramp-up phases. Furthermore, institutional discussions on ValuePickr and Reddit r/IndianStockMarket suggest that timely execution of HAM projects will be a vital determinant for sustaining return on capital employed (ROCE) above sector averages.
Peer Comparison: Valuation and Execution Benchmarks
| Company / Peer Name | P/E Ratio | Order Book / Scale | Key Note |
|---|---|---|---|
| Ceigall India | 18.5x | ₹9,400 Cr | Specialized in elevated corridors and urban expressways. |
| PNC Infratech | 14.2x | ₹15,000+ Cr | Established road contractor with diversified asset monetization. |
| HG Infra Engineering | 19.1x | ₹11,000+ Cr | Known for strong execution efficiency and asset-light models. |
Peer valuation data sourced from Screener.in and Trendlyne.
Bull vs. Bear Catalysts
Growth Catalysts (Bull Case)
- Robust ₹9,400+ crore order book providing revenue visibility for the next 24 to 36 months.
- Strong execution track record in complex elevated structures, commanding superior operating margins.
- Deleveraged balance sheet post-IPO providing necessary headroom for aggressive NHAI bidding.
Key Downside Risks (Bear Case)
- Execution delays in HAM projects due to land acquisition or environmental clearance bottlenecks.
- Intense competitive intensity from larger tier-1 road construction peers in upcoming NHAI tenders.
- Potential volatility in raw material costs (steel and bitumen) impacting quarterly EBITDA margins.
Investment Analytical Verdict
Suitable For: Long-term institutional and core growth investors
Risk Level: Medium — Execution efficiency and timely working capital realization remain key variables
Key Watch Point: Quarterly conversion rate of order book into actual billings and cash flows
Frequently Asked Questions
How does Ceigall India’s valuation compare to established road construction peers?
Ceigall India trades at a P/E multiple of approximately 18.5x, aligning closely with specialized peers like HG Infra Engineering while maintaining strong order book backing. Its focus on specialized elevated corridors justifies the valuation premium over traditional highway builders.
What is the current status of Ceigall India’s order book and execution capacity?
The company’s order book stands well above ₹9,400 crore, concentrated heavily in high-margin elevated highway and metro structures. Post-listing capital infusion has further bolstered its balance sheet to handle larger project scales.
What are the primary risk factors for investors tracking Ceigall India?
Key risks include potential delays in land acquisition for HAM projects, intense bidding competition from tier-1 players in upcoming NHAI tenders, and fluctuations in raw material input costs affecting operational margins.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: Chittorgarh, Moneycontrol, Livemint, BSE India filings, Screener.in