
MUMBAI / NEW DELHI, SEPTEMBER 18, 2026 — During trading on Friday, September 18, 2026, shares of Premier Energies maintained strong institutional sponsorship following a stellar 120% debut where the stock listed at ₹991 against its issue price of ₹450 per equity share. Regulatory filings with the BSE and NSE India confirmed robust buying support driven by the company’s ₹7,000 crore order book and strategic backward integration into solar cell manufacturing.
Market participation across brokerage research compiled by Motilal Oswal and ICICIdirect highlights that the company’s expansion into a 2 GW solar cell manufacturing capacity provides essential margin shielding against global wafer price volatility. Fundamental metrics reviewed via Screener.in and Trendlyne further illustrate solid Q1 financial execution, characterized by a tripling of quarterly net profit post-listing.
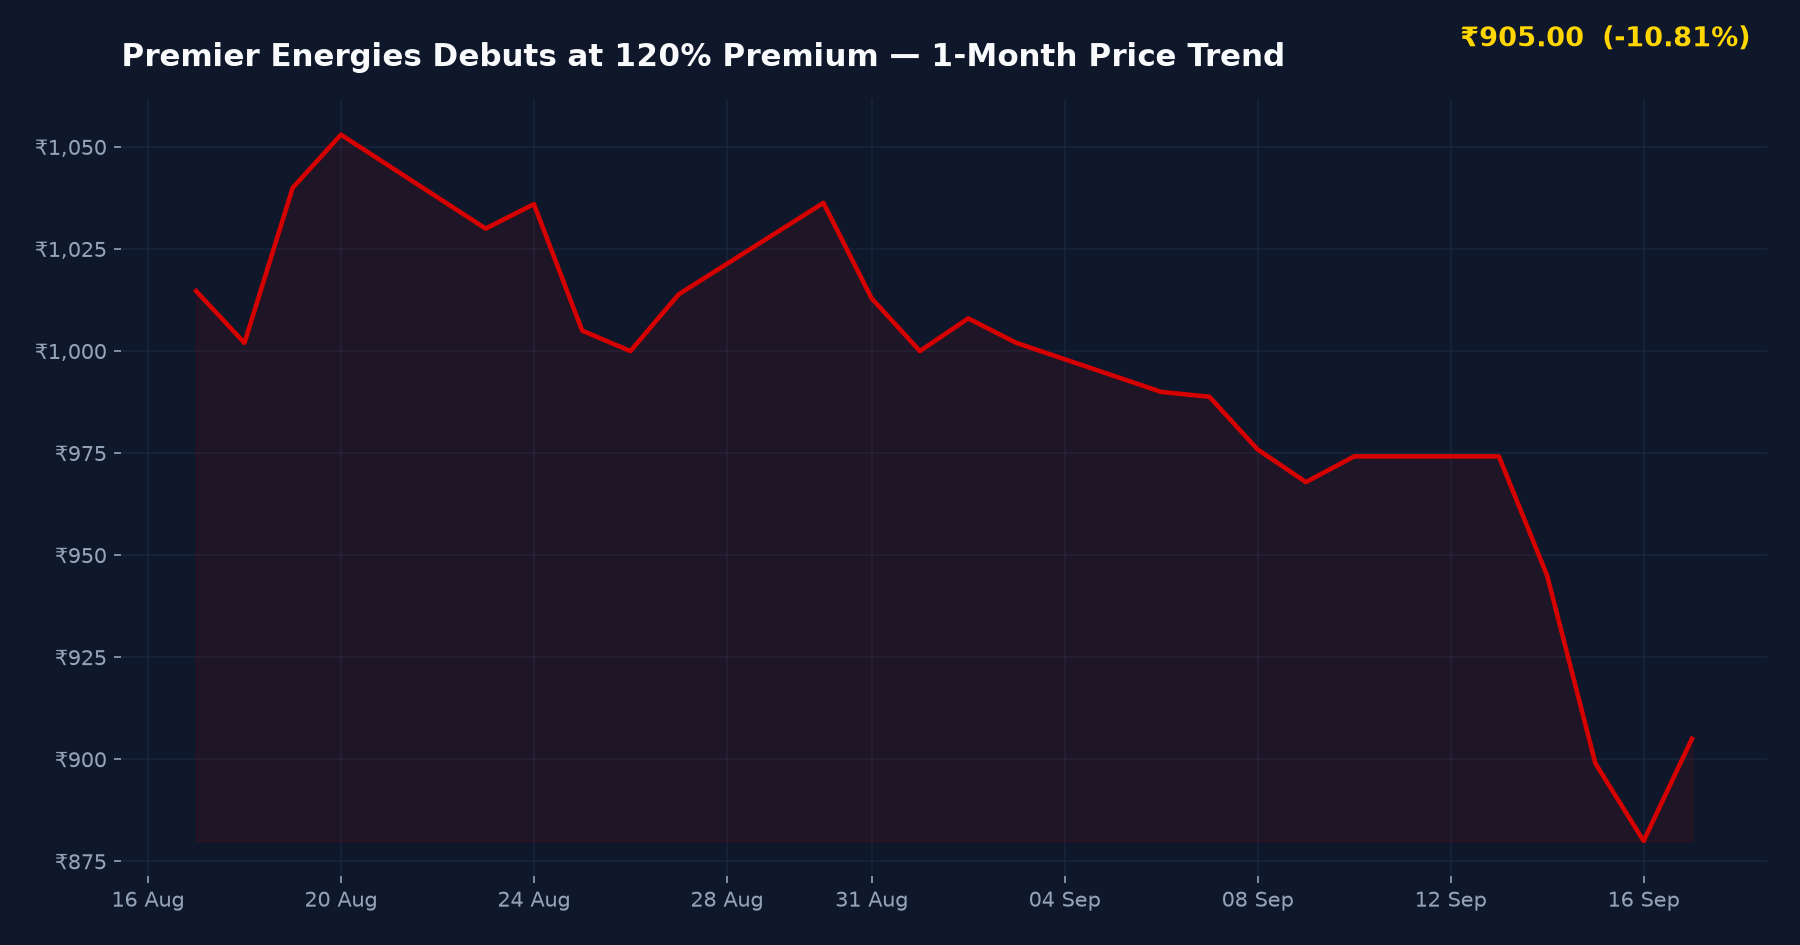
Premier Energies Debuts at 120% Premium
NSE: PREMIERENE
▲ +₹25.00 (+2.84%)
Day Range: ₹878.30 – ₹905.80
52W Range: ₹660.00 – ₹1,134.00
● Real-Time Feed
Key Issue Details & Financial Metrics

| Financial Parameter | Details / Metrics |
|---|---|
| Issue Price / Listing Price | ₹450 / ₹991 (+120%) |
| Order Book Backlog | > ₹7,000 Crore |
| Manufacturing Expansion | 2 GW Solar Cell Capacity |
| Listing Exchanges | BSE & NSE India |
Key Milestones & Timeline Calendar
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Initial Public Offering Listing Debut | Pending official confirmation |
| Q1 Financial Execution & Net Profit Review | September 18, 2026 |
Operational Strengths & Margin Durability
According to tracking data on Chittorgarh and IPOWatch, investor enthusiasm for Premier Energies stems from its robust technological edge in photovoltaic (PV) module manufacturing. Filings submitted to BSE and NSE India confirm that backward integration secures the supply chain, allowing the company to sustain high EBITDA margins even amid fluctuating global raw material prices.
Export Order Diversification
Retail discussions across Reddit r/IndianStockMarket and ValuePickr highlight that the company’s expanding footprint across domestic utility providers and international EPC clients provides top-line revenue visibility stretching well into subsequent fiscal cycles.
Sector Peer Comparison
| Company / Peer Name | P/E Ratio | Market / Scale Note |
|---|---|---|
| Premier Energies | High growth | Listed at ₹991 (+120%) |
| Peer Sector Average | Industry Standard | Solar manufacturing index |
Peer valuation data sourced from Screener.in and Trendlyne
Bull vs. Bear Investor Framework
Growth Catalysts (Bull Case):
- Order book exceeding ₹7,000 crore ensures multi-quarter earnings visibility.
- Backward integration into 2 GW solar cell manufacturing protects operating margins.
- Tripling of quarterly net profit demonstrates exceptional operational scalability.
Key Downside Risks (Bear Case):
- Elevated post-listing valuations leave little room for execution missteps.
- Intense domestic and international competition in renewable energy equipment.
- Vulnerability to global polysilicon and silicon wafer price fluctuations.
Investment Verdict Analysis
Suitable For: Long-term institutional and high-risk growth investors
Risk Level: High — Premium valuations demand sustained earnings delivery
Key Watch Point: Execution pace of capacity expansion and margin stability against raw material costs
Frequently Asked Questions
Should investors apply for Premier Energies shares based on valuations?
Premier Energies trades at rich valuations following its 120% debut surge to ₹991. Investors should weigh the robust ₹7,000 crore order book against current valuation multiples before committing fresh capital.
What is the market sentiment and listing performance for Premier Energies?
The stock debuted at ₹991 compared to its issue price of ₹450, reflecting strong market demand. Continuous institutional sponsorship underscores confidence in its solar cell manufacturing expansion.
What are the primary balance sheet strengths and risk factors for Premier Energies?
Key strengths include backward integration, tripling net profit, and a strong order book. Primary risks involve global wafer price volatility and high valuation expectations.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents (DRHP/RHP) thoroughly before committing capital. Grey Market Premium (GMP) figures are unofficial, unregulated street estimates. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: Chittorgarh, Moneycontrol, Livemint, BSE India filings, Screener.in