
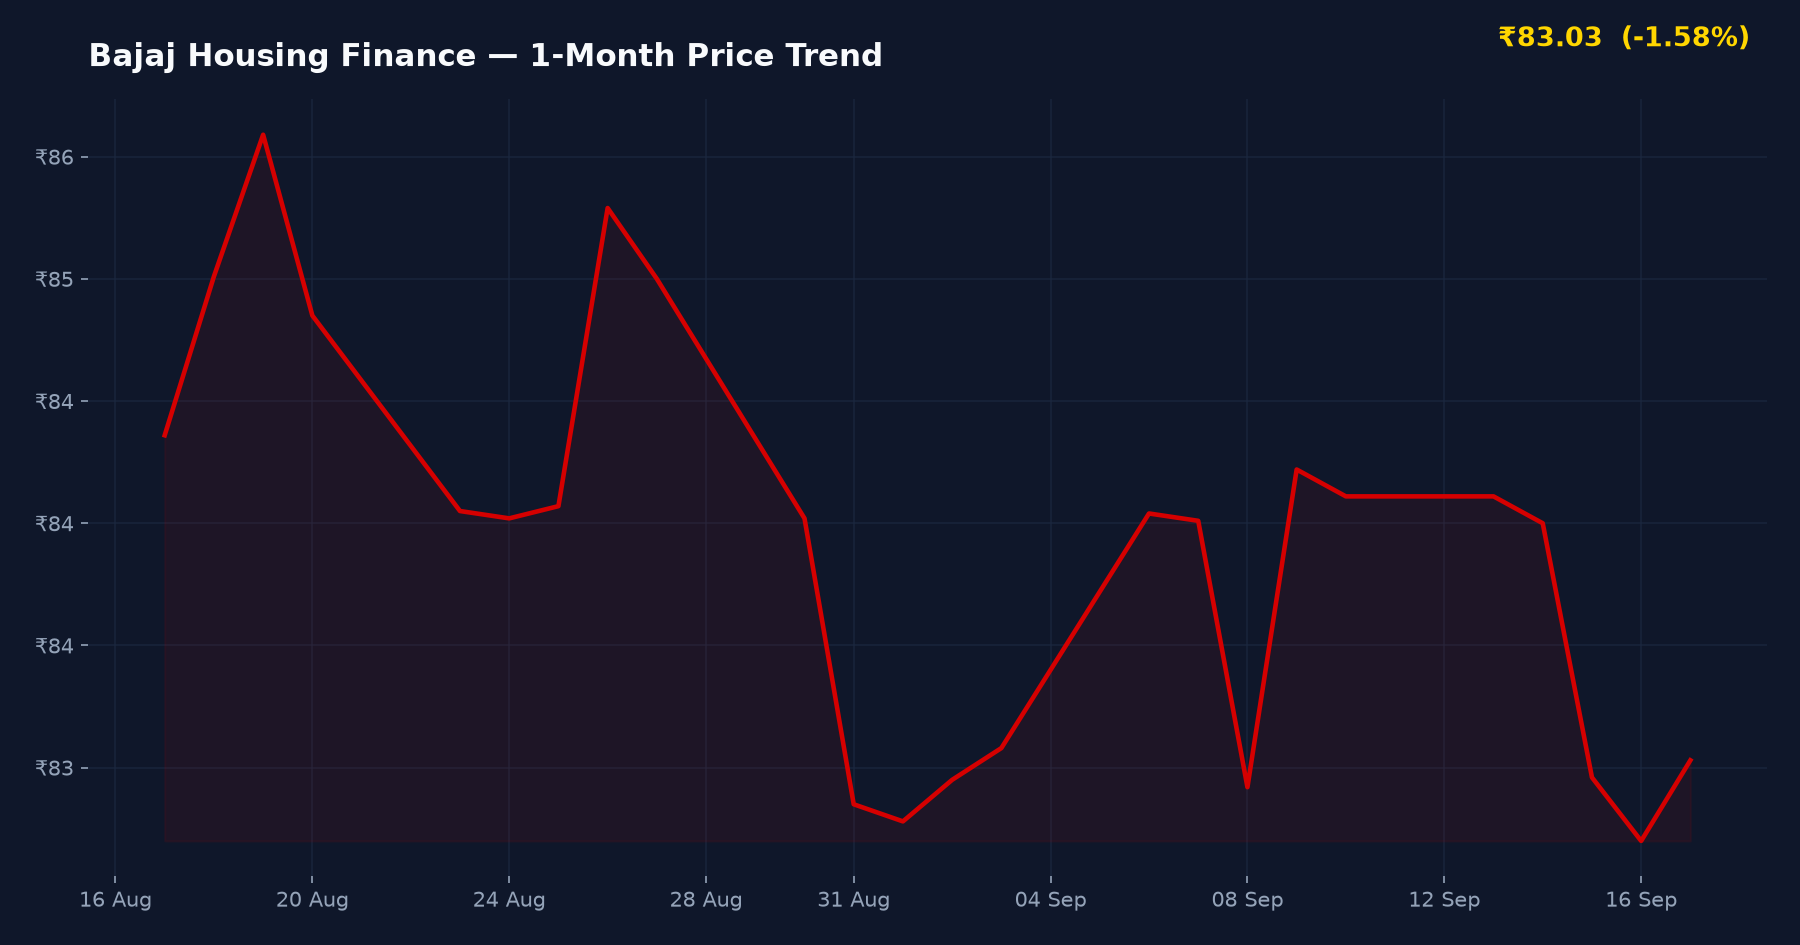
MUMBAI / NEW DELHI, SEPTEMBER 18, 2026 — During trading on Friday, September 18, 2026, shares of Bajaj Housing Finance experienced institutional consolidation following a historic market debut that initially saw the stock double from its ₹70 issue price to ₹150 on listing day. According to regulatory filings submitted to the BSE and NSE India, the company maintains defensive balance sheet characteristics underpinned by prime mortgage growth and pristine asset quality metrics.
Bajaj Housing Finance
NSE: BAJAJHFL
▲ +₹0.33 (+0.40%)
Day Range: ₹82.71 – ₹83.17
52W Range: ₹72.65 – ₹114.95
● Real-Time Feed
Key Milestones & Timeline Calendar

| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Initial Public Offering Listing Debut | September 16, 2024 |
| Post-Listing Institutional Consolidation Review | September 18, 2026 |
Key Financial Parameters & Balance Sheet Metrics
| Financial Metric | Value / Ratio |
|---|---|
| Original Issue Price | ₹70.00 |
| Listing Day High | ₹150.00 |
| Gross NPA Ratio | ~0.28% |
| Primary Focus Segment | Salaried Home Loans |
| Listing Exchanges | BSE & NSE |
Asset Quality & Prime Mortgage Growth Analysis
According to fundamental metrics compiled from Screener.in and Trendlyne, Bajaj Housing Finance continues to maintain the lowest gross non-performing asset (NPA) ratio among major housing finance companies in India, standing at approximately 0.28%. Brokerage research from Motilal Oswal and ICICIdirect indicates that the high proportion of salaried borrowers within its loan book provides robust insulation against macroeconomic headwinds and cyclical downturns.
Evaluating Net Interest Margin (NIM) Dynamics
Market tracking data across Moneycontrol and Livemint highlights that the company’s efficient cost of borrowings, backed by the strong parentage of Bajaj Finance, allows it to sustain competitive lending rates while protecting its net interest margins. Retail sentiment discussed across platforms like Reddit r/IndianStockMarket and ValuePickr emphasizes that while valuations remain elevated compared to midcap housing peers, the superior return on equity (RoE) justifies the structural premium.
Peer Valuation Comparison
| Company / Peer Name | P/B Multiple | Gross NPA | Key Note |
|---|---|---|---|
| Bajaj Housing Finance | Premium | 0.28% | Lowest NPA & high salaried mix |
| Can Fin Homes | Moderate | ~0.90% | Established retail franchise |
| LIC Housing Finance | Discount | ~2.50% | Larger book, higher legacy risks |
Peer valuation data sourced from Screener.in and Trendlyne.
Bull vs. Bear Investor Framework
Growth Catalysts (Bull Case)
- Industry-leading asset quality with gross NPAs anchored near 0.28%.
- Strong concentration of high-credit-profile salaried home loan borrowers.
- Robust parental backing ensuring competitive borrowing costs and liquidity access.
Downside Risks (Bear Case)
- Rich price-to-book valuation multiple leaves little room for earnings disappointment.
- Intense competition in the prime mortgage segment from major banking institutions.
- Potential margin compression in a fluctuating interest rate environment.
Investment Verdict & Analytical Summary
Suitable For: Long-term institutional and growth-oriented equity investors
Risk Level: Medium — High valuation multiples require sustained earnings compounding to justify current pricing.
Key Watch Point: Ongoing NIM stability and quarterly asset quality metrics across future earnings prints.
Frequently Asked Questions
Should investors buy Bajaj Housing Finance shares at current valuations?
The stock currently trades at a valuation premium compared to historical sector averages, reflecting its pristine asset quality and high-growth salaried portfolio. Long-term investors should assess their risk appetite and consider accumulating on dips rather than chasing sharp intraday rallies.
How does Bajaj Housing Finance maintain lower NPAs than peers?
The company focuses heavily on prime salaried home loan customers who possess stable credit profiles and lower default probabilities. Strict underwriting standards and robust digital verification further insulate its lending book.
What are the primary risk factors affecting housing finance margins?
Key risks include rising wholesale funding costs, aggressive lending rate compression by commercial banks, and potential macroeconomic pressures impacting real estate demand.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: Chittorgarh, Moneycontrol, Livemint, BSE India filings, Screener.in