
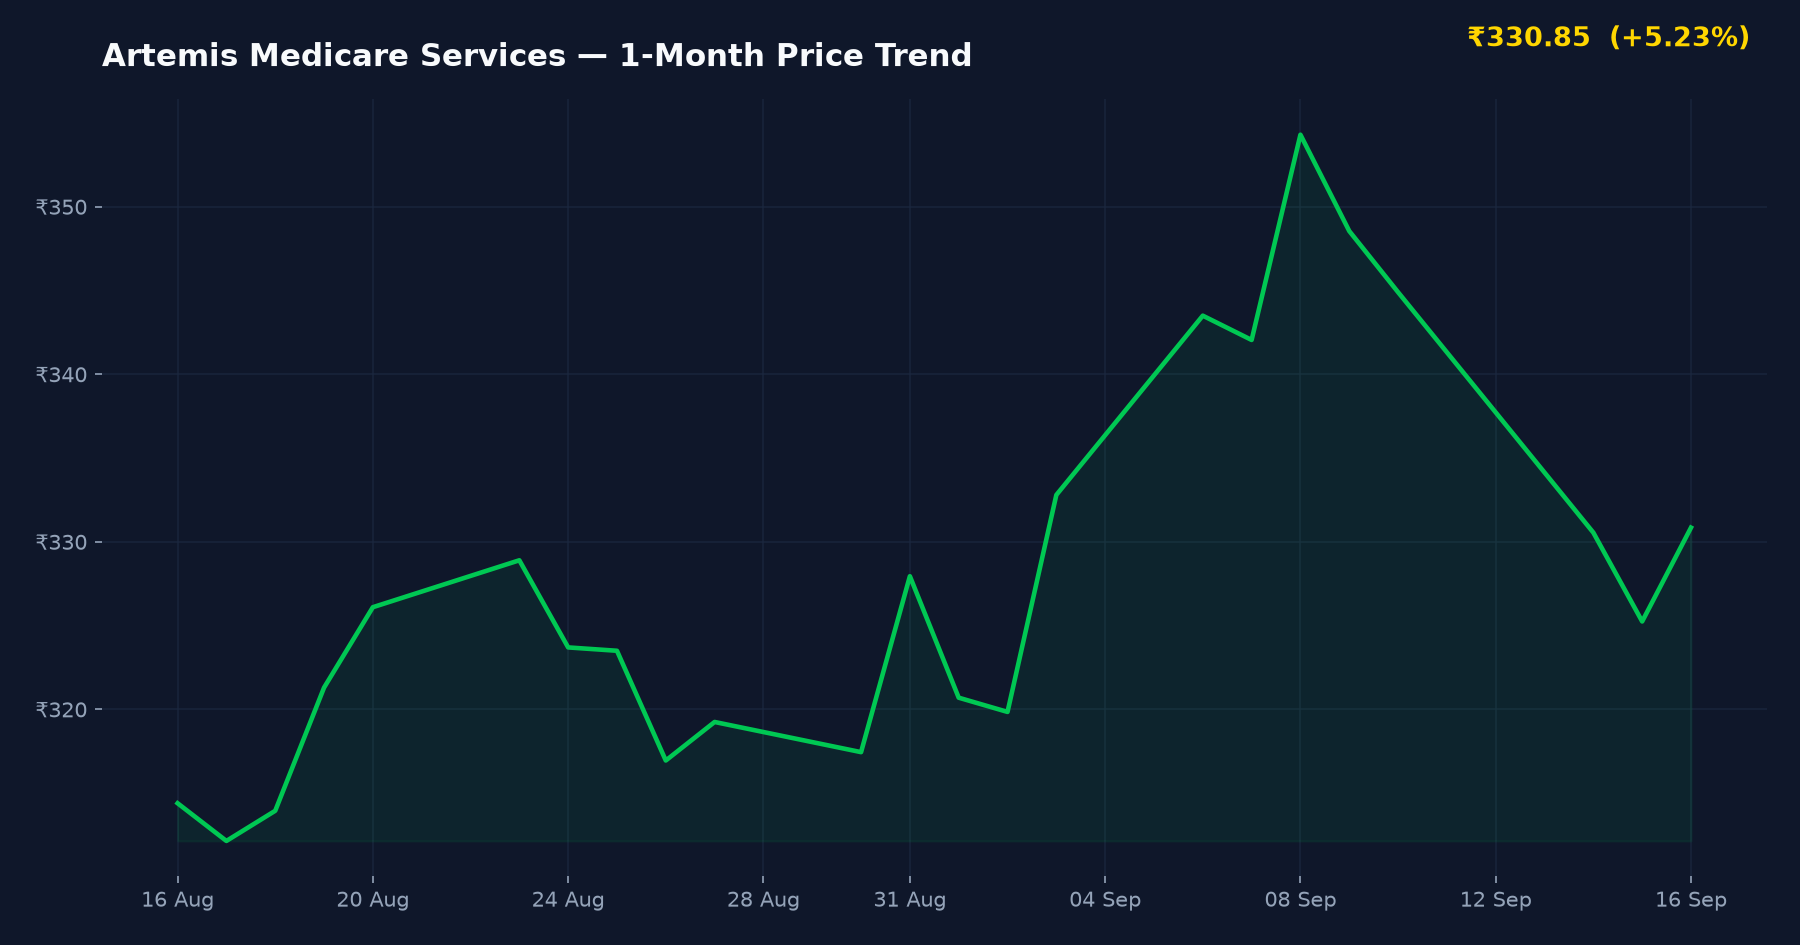
MUMBAI / NEW DELHI, SEPTEMBER 18, 2026 — During trading on Friday, September 18, 2026, shares of Artemis Medicare Services continued to draw strong institutional and retail attention following a robust 26% rally over the preceding three months. Backed by strategic capital-raising initiatives through Qualified Institutional Placements (QIP) and ambitious capacity expansion blueprints targeting nearly 2,000 operational beds by 2030, analysts from leading brokerages maintain a positive outlook with projected upside targets near ₹325 per share.
Artemis Medicare Services
NSE: ARTEMISMED
▲ +₹5.60 (+1.72%)
Day Range: ₹324.25 – ₹338.80
52W Range: ₹203.35 – ₹362.00
● Real-Time Feed
Key Corporate Milestones & Timeline

| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Standalone March 2026 Net Sales Print (Rs 273.79 Crore) | May 11, 2026 |
| QIP Fundraise Announcement (Rs 700 Crore Target) | March 2, 2026 |
| Brokerage Institutional Coverage Update (Choice Equities) | February 4, 2026 |
Key Financial Parameters & Metrics
| Financial Metric | Data Point |
|---|---|
| 3-Month Stock Price Gain | 26.0% |
| Target Price Issued by Institutional Research | ₹325.00 |
| Proposed QIP Capital Raising Target | ₹700 Crore |
| Target Bed Capacity by 2030 | ~2,000 Beds |
| Standalone Q4 Net Sales (March 2026) | ₹273.79 Crore |
In-Depth Fundamental Analysis & Strategic Growth Catalysts
According to fundamental metrics compiled on Screener.in and Trendlyne, Artemis Medicare Services has exhibited steady revenue growth, anchored by its standalone net sales reaching ₹273.79 crore for the quarter ended March 2026, marking a 16.6% year-on-year increase. Market participants tracking corporate developments via Moneycontrol and Livemint note that the management’s aggressive blueprint to raise up to ₹700 crore via a Qualified Institutional Placement (QIP) is designed to triple existing bed capacity.
International Patient Inflows and Utilization Efficiencies
Brokerage research compiled by Choice Institutional Equities highlights that higher occupancies across mature facilities, combined with a steady influx of international medical tourists, are driving operating margins. As new hospital units move through their gestation periods toward optimal utilization, return ratios are expected to strengthen significantly.
Peer Valuation Benchmarks
| Hospital Peer Name | P/E Ratio / Context | Key Strategic Note |
|---|---|---|
| Apollo Hospitals Enterprise | Industry Benchmark | Omnichannel healthcare leader |
| Max Healthcare Institute | Premium Valuation | High ARPOB and regional dominance |
| Artemis Medicare Services | Growth Phase | Expanding bed capacity to ~2,000 |
Peer valuation data sourced from Screener.in and Trendlyne.
Balanced Investor Framework: Bull vs. Bear Catalysts
Bullish Growth Catalysts
- Aggressive Expansion: Plans to scale operating bed capacity toward 2,000 units by 2030, enhancing long-term revenue visibility.
- Strong Financial Momentum: Standalone net sales for March 2026 grew 16.6% year-on-year to ₹273.79 crore.
- Institutional Backing: Brokerage research from Choice Institutional Equities maintains a target price of ₹325 per share.
Key Downside Risks
- Execution Delays: Greenfield and brownfield hospital expansions are susceptible to construction and regulatory approval delays.
- Equity Dilution: The proposed ₹700 crore QIP fundraise could lead to short-term equity dilution for existing shareholders.
- Gestation Pressures: Newly commissioned facilities often experience initial operating losses during the ramp-up phase.
Analytical Investment Verdict
Suitable For: Medium-to-long-term growth investors with an appetite for healthcare infrastructure expansion.
Risk Level: Medium — Execution efficiency of the ₹700 crore QIP and new bed ramp-ups dictate near-term performance.
Key Watch Point: Progress on the announced capacity expansion timeline toward 2,000 beds by 2030.
Frequently Asked Questions
What is the growth outlook for Artemis Medicare Services stock?
Artemis Medicare shares have rallied 26% over a three-month period, supported by robust quarterly financial numbers and expansion plans targeting nearly 2,000 operational beds by 2030. Institutional brokers maintain a positive stance with target prices estimated around ₹325.
How is Artemis Medicare funding its hospital expansion plans?
The company announced plans to raise approximately ₹700 crore through a Qualified Institutional Placement (QIP) to fund its multi-facility expansion and triple its bed capacity over the coming years.
What are the primary risks associated with investing in Artemis Medicare?
Key risks include potential project execution delays, gestation costs associated with new medical facilities, and equity dilution resulting from the proposed QIP capital-raising initiative.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: Moneycontrol, Livemint, Economic Times, Screener.in, Trendlyne, BSE India filings.