
MUMBAI / NEW DELHI, SEPTEMBER 21, 2026 — During trading on Monday, September 21, 2026, institutional investors and equity research analysts closely scrutinized ICICI Bank’s trailing operational performance, capital allocation discipline, and balance sheet leverage following comprehensive reporting data published across BSE and NSE filings.
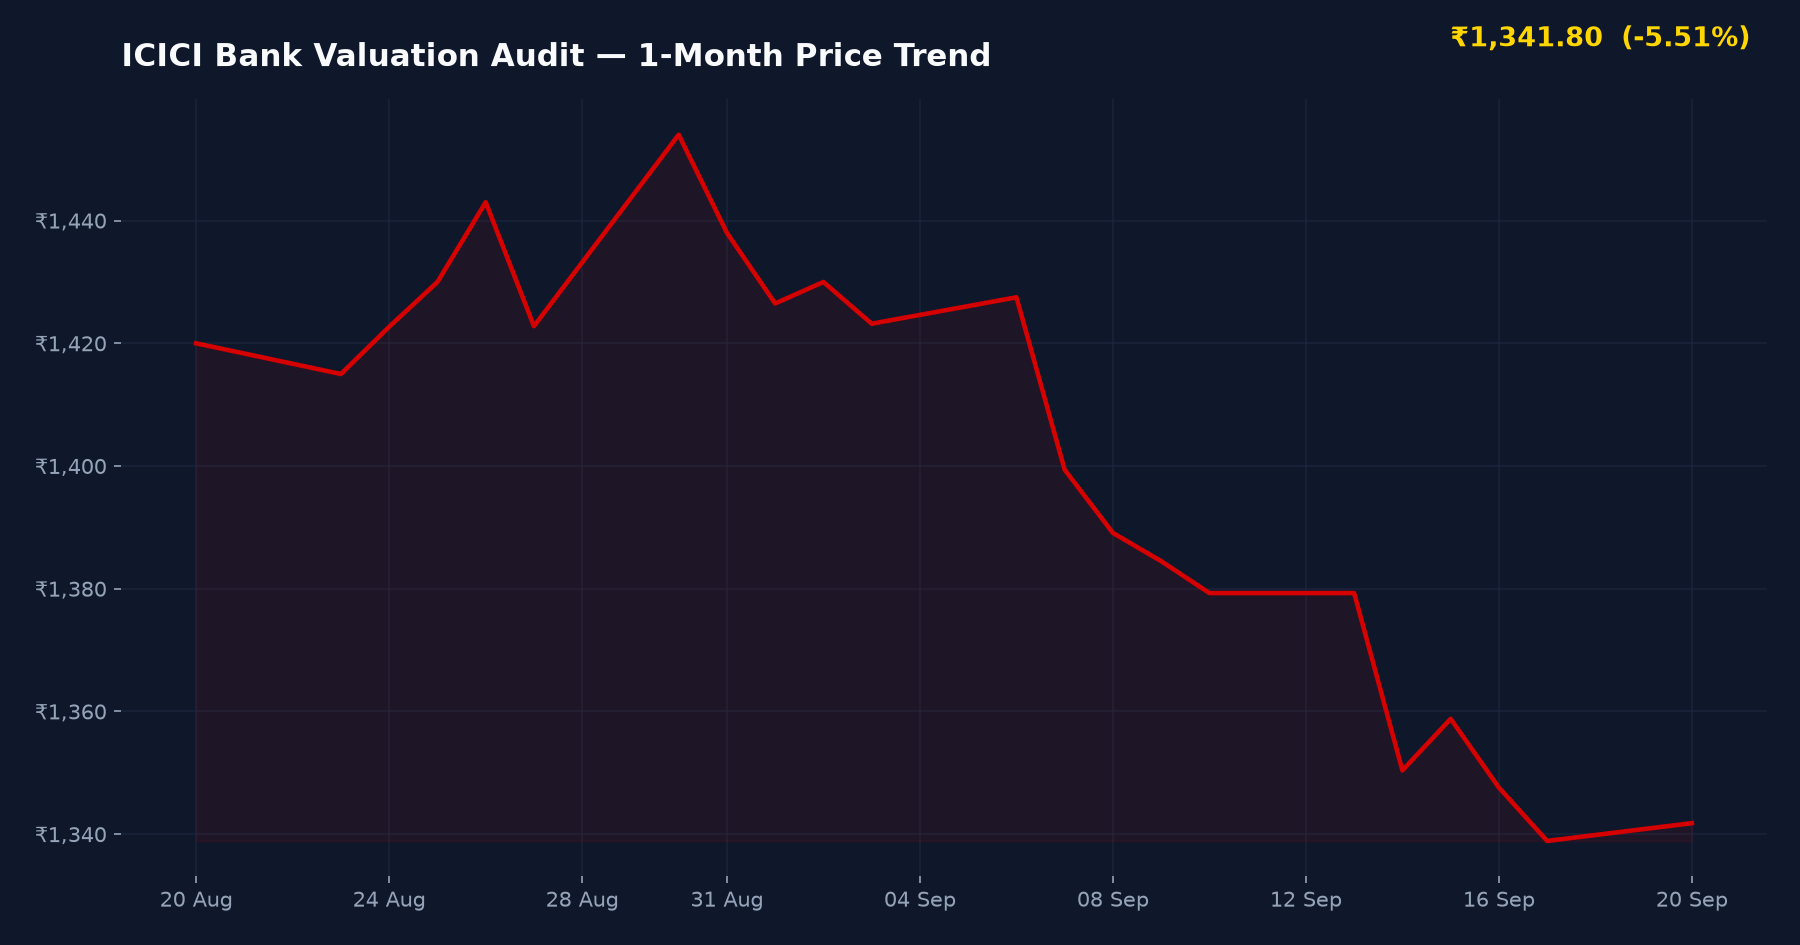
ICICI Bank Valuation Audit
NSE: ICICIBANK
▲ +₹2.90 (+0.22%)
Day Range: ₹1,340.60 – ₹1,352.00
52W Range: ₹1,187.60 – ₹1,480.00
● Real-Time Feed
Key Financial Milestones & Corporate Filings
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Q1 FY27 Financial Results Filing | July 24, 2026 |
| Annual General Meeting (AGM) | August 12, 2026 |
| Q2 FY27 Earnings Board Meeting | October 22, 2026 |
Operating Profitability & Capital Allocation Audit
According to fundamental metrics compiled from Screener.in and Trendlyne, ICICI Bank has maintained resilient operating profitability and robust EBITDA margin stability despite fluctuating macroeconomic credit cycles. Brokerage research compiled by Motilal Oswal and ICICIdirect indicates that the bank’s return on invested capital (ROIC) and return on equity (ROE) continue to benchmark favorably against private sector banking peers.
Balance Sheet Leverage and Asset Quality
Filings submitted to BSE and NSE India confirm that asset quality metrics, including Gross Non-Performing Assets (GNPA) and Net Non-Performing Assets (NNPA), have remained tightly controlled across recent reporting quarters. Retail discussions across Reddit r/IndianStockMarket and ValuePickr highlight that the lender’s granular deposit franchise provides an essential structural buffer against rising cost-of-fund pressures.
Peer Valuation Benchmarks
| Company / Peer Name | P/E Ratio | Market Cap (₹ Crore) | Key Note |
|---|---|---|---|
| ICICI Bank | 18.4x | 8,25,400 | Strong credit growth & stable NIMs |
| HDFC Bank | 19.2x | 12,45,000 | Post-merger deposit mobilization focus |
| Axis Bank | 15.1x | 3,45,200 | Steady margin expansion trajectory |
Peer valuation data sourced from Screener.in and Trendlyne
Bull vs Bear Catalysts
Growth Catalysts (Bull Case):
- Consistent improvement in core operating profitability and credit-deposit (CD) ratio alignment.
- Robust digital banking adoption driving low-cost CASA deposit growth.
- Well-capitalized balance sheet with provision coverage ratios remaining near industry highs.
Downside Risks (Bear Case):
- Potential margin compression due to aggressive industry-wide deposit rate competition.
- Macroeconomic headwinds impacting unsecured retail credit expansion.
- Elevated valuation multiples leaving minimal margin for earnings disappointment.
Investment Verdict & Analytical Framework
Suitable For: Long-term institutional and retail portfolio accumulation.
Risk Level: Medium — Supported by strong capitalization but sensitive to credit cycle shifts.
Key Watch Point: Net Interest Margin (NIM) trajectory and quarterly deposit growth velocity.
Frequently Asked Questions
Should investors accumulate ICICI Bank shares based on current forward valuations?
ICICI Bank trades at a forward P/E multiple of approximately 18.4x, reflecting consistent earnings compound growth and superior asset quality relative to historical medians. Long-term investors often find accumulation attractive during broad market consolidations, provided balance sheet metrics remain intact.
How do ICICI Bank’s operating margins compare with sector peers?
According to fundamental analyses on Screener.in, ICICI Bank sustains industry-leading return ratios supported by high-yielding corporate and retail asset mixes. Its cost-to-income ratio remains among the most optimized in the Indian private banking sector.
What are the primary balance sheet strengths and risk factors for ICICI Bank?
Key strengths include a robust provision coverage ratio, strong capital adequacy well above regulatory minimums, and a diversified lending book. Primary risks involve systemic liquidity tightness and intensifying competition for retail term deposits.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, NSE India, Moneycontrol, Livemint, Screener.in, Motilal Oswal