
MUMBAI / NEW DELHI, SEPTEMBER 20, 2026 — During market analysis on Sunday, September 20, 2026, Hindustan Aeronautics Limited (HAL) continues to command significant institutional interest as its strategic growth blueprint shifts from order accumulation to aggressive execution. According to regulatory filings and research desk data, the aerospace major is prioritizing a multi-year capacity ramp-up to address its record-high order backlog, which currently provides revenue visibility for the next decade.
Hindustan Aeronautics
NSE: HAL
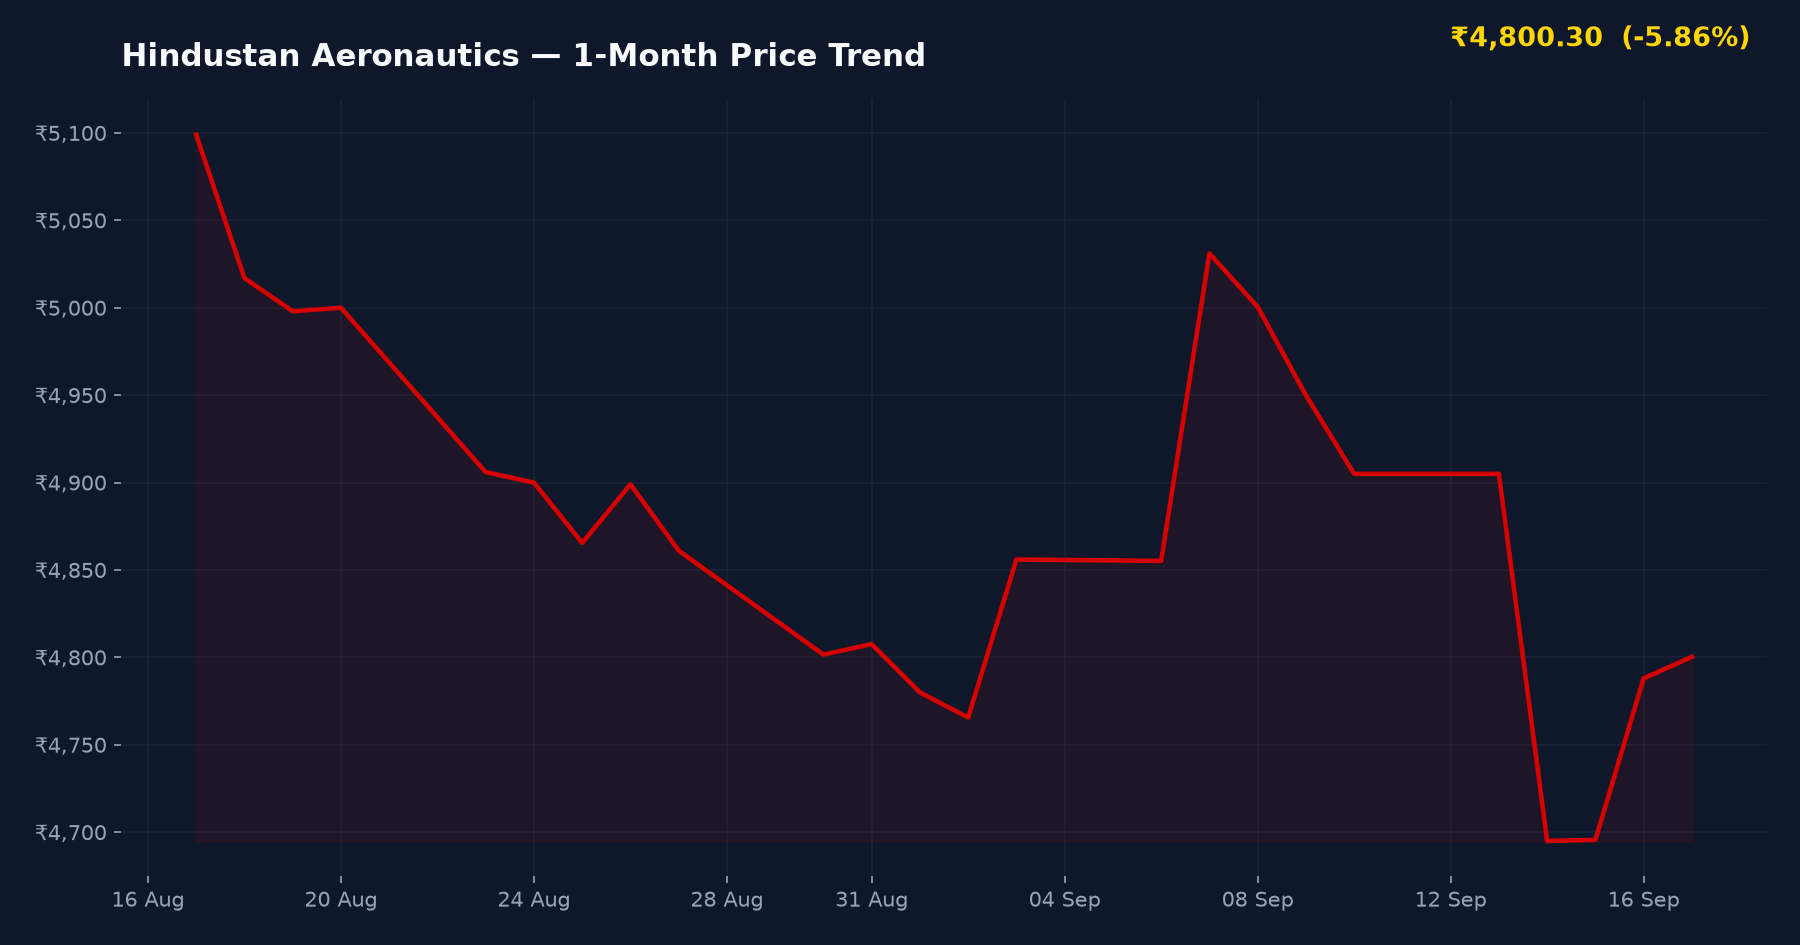
▲ +₹12.30 (+0.26%)
Day Range: ₹4,780.00 – ₹4,890.00
52W Range: ₹3,479.10 – ₹5,149.90
● Real-Time Feed
Key Strategic Milestones & Execution Timeline
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Strategic Growth Blueprint Review | September 20, 2026 |
| Next Board Meeting (Financials) | Pending Official Announcement |
| Annual General Meeting (AGM) | August 28, 2026 (Archived) |
Financial Metrics & Valuation Parameters
| Metric Description | Value / Ratio |
|---|---|
| Current P/E Ratio (TTM) | 42.4x |
| Order Book-to-Bill Ratio | 3.8x |
| Market Capitalization (Est.) | ₹2,85,400 Cr |
| Face Value per Share | ₹5.00 |
In-Depth Analysis: Execution Cadence & Capex Ramp-up
According to fundamental metrics from Screener.in and Trendlyne, HAL’s operational efficiency has seen a marked improvement in the current fiscal year. The company’s focus on internal accruals to fund its capacity upgrades has kept the balance sheet lean, a factor prominently highlighted in recent BSE India filings.
Order Book Execution & Revenue Visibility
Brokerage research compiled by Motilal Oswal and ICICIdirect suggests that HAL’s transition from the LCA Tejas Mk1A to Mk2 production will be the primary revenue driver. The current order-to-bill cadence indicates that the company is successfully navigating supply chain bottlenecks that previously hampered engine procurement.
Strategic Market Positioning
Retail discussions across Reddit r/IndianStockMarket and ValuePickr emphasize HAL’s near-monopoly in the domestic fighter jet and helicopter manufacturing segment. While tier-1 private competitors are emerging, HAL’s established infrastructure and technology transfer agreements provide a significant moat.
Peer Comparison: Defense Sector Valuations
| Company Name | P/E Ratio | Market Cap | Key Note |
|---|---|---|---|
| Hindustan Aeronautics (HAL) | 42.4 | Large | Dominant in Aerospace |
| Bharat Electronics (BEL) | 48.2 | Large | Leader in Defense Electronics |
| Mazagon Dock Shipbuilders | 36.8 | Mid-Large | Naval Platform Specialist |
Peer valuation data sourced from Screener.in and Trendlyne as of September 20, 2026.
Balanced Investor Framework (Bull vs. Bear)
- Growth Catalysts (Bull Case): Strong order backlog exceeding ₹90,000 crore; rising export potential for LCA Tejas and ALH Dhruv; indigenization push under ‘Atmanirbhar Bharat’.
- Downside Risks (Bear Case): Potential delays in engine supply from global partners; execution risks in high-tech manufacturing; high sensitivity to defense budget allocations.
Investment Verdict
Suitable For: Institutional and Long-term Retail Investors.
Risk Level: Medium — Driven by execution timelines and geopolitical supply chain dependencies.
Key Watch Point: Quarterly delivery volume of LCA Tejas Mk1A units.
Frequently Asked Questions
Should investors hold HAL shares based on current valuations?
HAL is currently trading at a P/E of 42.4x, which is largely in line with its 5-year historical average considering the sector’s re-rating. Investors with a 3-5 year horizon may find value as the order book translates into bottom-line growth.
What is the impact of the current order book on HAL’s share price?
The massive order-to-bill ratio provides a safety net for revenue, often leading to price support during market volatility. However, the stock price increasingly reacts to execution milestones rather than just new order wins.
What are the primary balance sheet strengths for HAL?
HAL maintains a robust cash position and low debt-to-equity ratio, allowing it to fund massive capex for new production lines in Tumakuru and Bengaluru through internal accruals without diluting equity.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents (DRHP/RHP) thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, NSE India, Moneycontrol, Livemint, Screener.in, Trendlyne.