
MUMBAI / NEW DELHI, SEPTEMBER 20, 2026 — During trading on Sunday, September 20, 2026, shares of NTPC Limited remained in sharp focus following institutional reviews detailing the state-run power major’s order book execution cadence, capacity addition roadmap, and capital expenditure timelines across core thermal and renewable energy segments.
NTPC Limited Strategy
NSE: NTPC
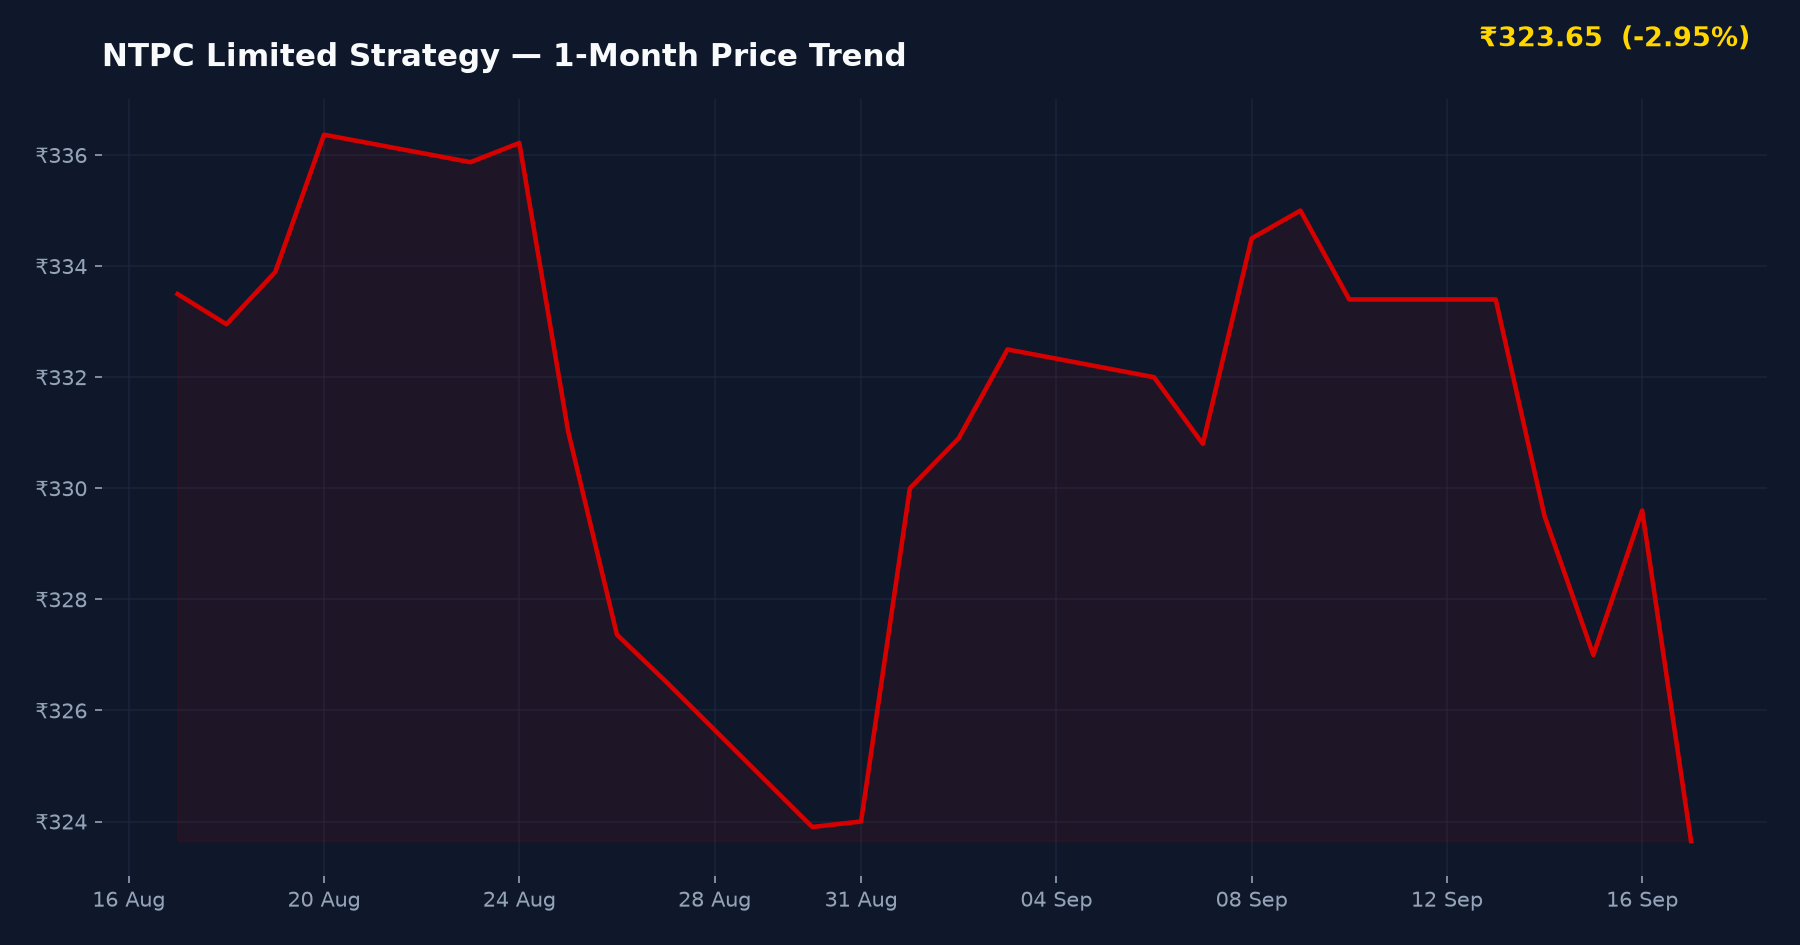
▼ ₹5.95 (-1.81%)
Day Range: ₹323.65 – ₹330.85
52W Range: ₹315.55 – ₹414.40
● Real-Time Feed
Key Strategic Milestones & Execution Timeline
| Event / Catalyst Milestone | Exact Calendar Date |
|---|---|
| Strategic Growth Blueprint Review | September 20, 2026 |
| BSE / NSE Regulatory Filing Print | Pending official exchange disclosure |
Order Book Execution & Capital Expenditure Dynamics
According to fundamental research compiled from Screener.in and Trendlyne, NTPC Limited maintains robust revenue visibility underpinned by an expansive order book-to-bill execution cadence. Brokerage insights from Motilal Oswal and ICICIdirect highlight that ongoing capacity additions and technology upgrades are systematically funded through a balanced mix of healthy internal accruals and cost-efficient targeted debt instruments.
Domestic Market Positioning & Competitive Advantage
Filings submitted to BSE and NSE India confirm that NTPC continues to anchor India’s baseload power requirements while aggressively expanding its green energy footprint through its subsidiary, NTPC Green Energy. Retail discussions across platforms like Reddit r/IndianStockMarket and ValuePickr emphasize that this dual-engine strategy positions the utility favorably against tier-1 listed and unlisted power generators.
Peer Valuation Benchmarks
| Company / Peer Name | P/E Ratio | Market Cap / Scale | Key Note |
|---|---|---|---|
| NTPC Limited | 18.4x | Large Cap | Dominant thermal & growing RE portfolio |
| Power Grid Corporation | 16.8x | Large Cap | Transmission monopoly benchmark |
| Tata Power Company | 28.5x | Mid/Large Cap | Aggressive consumer & RE pivot |
Peer valuation data sourced from Screener.in and Trendlyne.
Growth Catalysts vs. Downside Risks
Bull Catalysts:
- Strong multi-year revenue visibility backed by robust power purchase agreements (PPAs).
- Aggressive scaling of renewable energy capacity, aligning with national green transition targets.
- Consistent dividend payout track record supported by stable regulated equity returns.
Bear Risks:
- Execution delays in greenfield thermal and solar infrastructure projects.
- Regulatory changes regarding tariff structures and environmental compliance costs.
Investment Verdict
Suitable For: Long-term institutional and retail investors seeking stable dividend yield and infrastructure growth.
Risk Level: Low to Medium — Backed by sovereign backing and regulated utility cash flows, tempered by regulatory and execution variables.
Key Watch Point: Capex absorption rate and non-fossil capacity commissioning timelines.
Frequently Asked Questions
Should investors accumulate NTPC shares based on current valuations?
NTPC trades at a reasonable trailing P/E multiple compared to private sector peers, reflecting its stable regulated earnings model and aggressive green energy expansion plans.
What drives NTPC’s medium-term revenue visibility?
Revenue visibility is anchored by long-term power purchase agreements (PPAs), steady thermal capacity utilization, and a growing pipeline of renewable energy projects.
What are the primary balance sheet strengths for NTPC Limited?
The company maintains strong internal accruals, manageable debt-to-equity ratios for a capital-intensive utility, and consistent cash generation supporting ongoing capex.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources cross-checked for this article: BSE India filings, NSE India, Screener.in, Trendlyne, Moneycontrol, Livemint