
MUMBAI, OCTOBER 28, 2026 — During afternoon trade on Wednesday, Vedanta Aluminium reported a 105% year-on-year surge in second-quarter net profit to ₹6,187 crore for Q2 FY27, supported by record production volumes, stronger operational realisations, and an 83% jump in operating earnings before interest, tax, depreciation, and amortisation (EBITDA). Revenue from operations expanded 41% year-on-year, while the company pared net debt by ₹3,090 crore on a sequential basis, according to corporate filings submitted to the National Stock Exchange (NSE) and BSE.
Key Takeaways at a Glance
- Net Profit Doubling: Q2 FY27 profit after tax reached ₹6,187 crore, climbing 105% year-on-year from the corresponding quarter of the previous fiscal.
- De-leveraging Milestones: Net debt contracted by ₹3,090 crore quarter-on-quarter, driven by strong operational cash generation and disciplined working capital.
- Operational Momentum: Revenue rose 41% year-on-year alongside an 83% expansion in operating EBITDA, buoyed by higher sales volumes and firm metal realisations.
Vedanta Aluminium Q2 Profit Jumps 105% to ₹6,187 Cr
NSE: VEDL
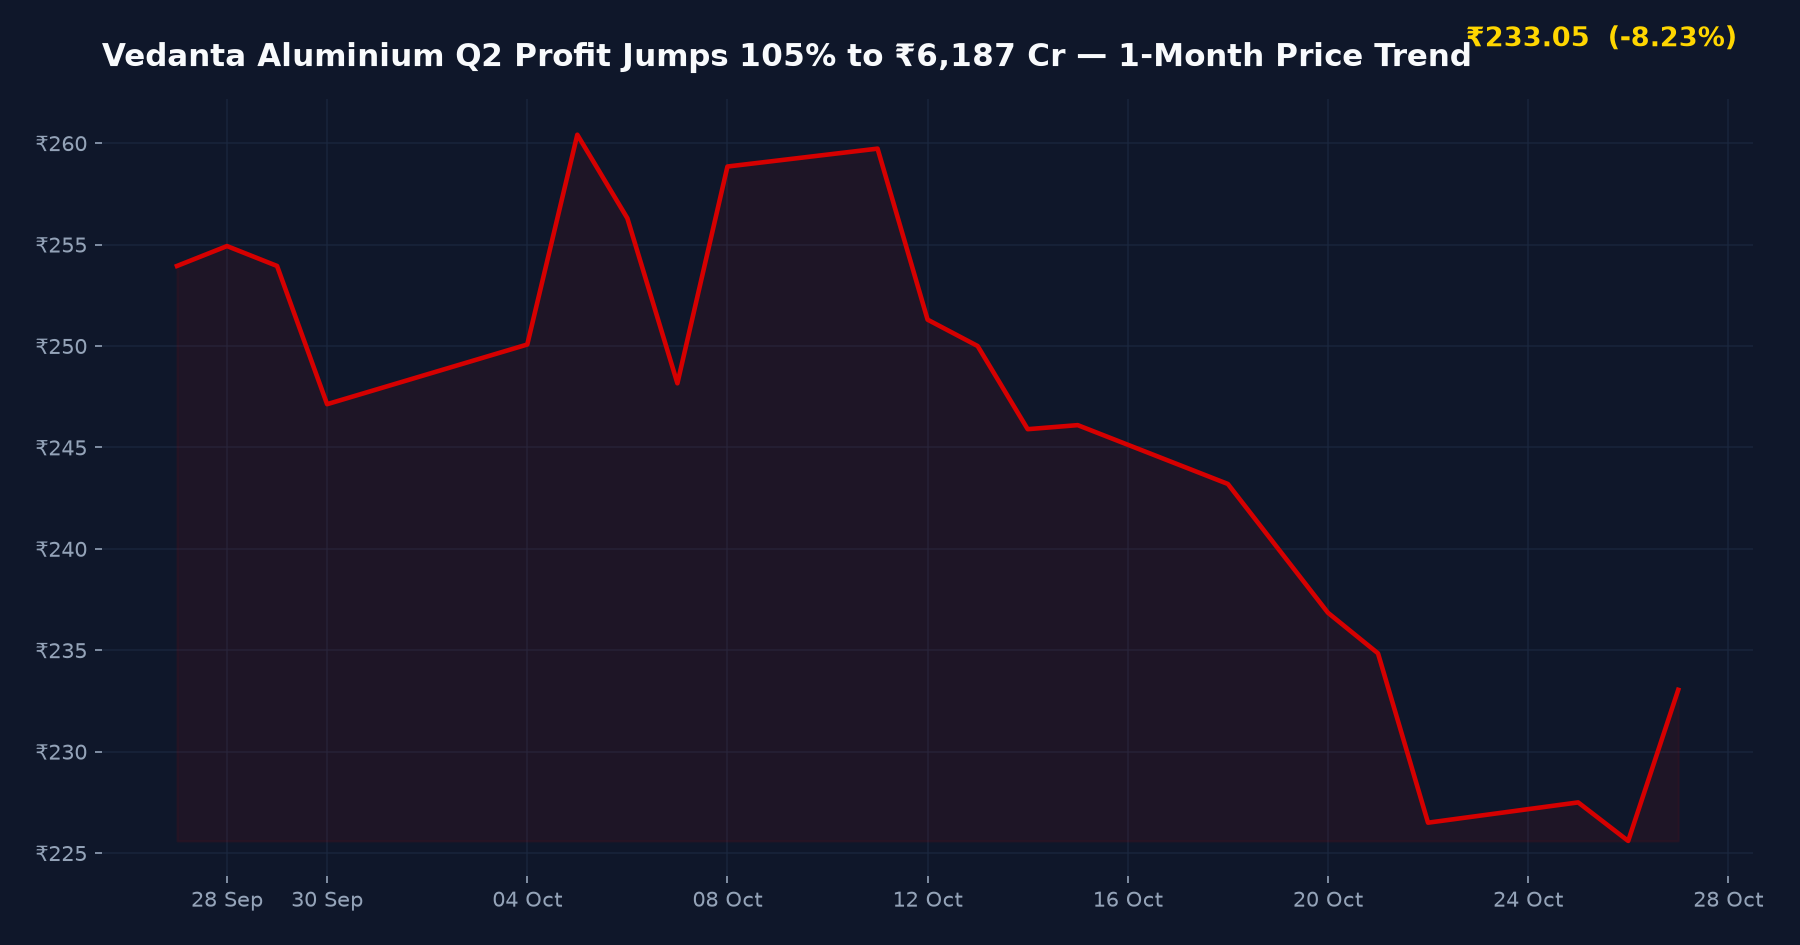
▲ +₹7.45 (+3.30%)
Day Range: ₹226.40 – ₹233.65
52W Range: ₹221.60 – ₹795.00
● Real-Time Feed
Earnings Calendar & Reporting Milestones
The quarterly earnings print follows a period of heightened scrutiny across metal counters on the Indian market indices dashboard. Below is the operational chronology and reporting schedule verified from regulatory exchange filings:
| Milestone / Corporate Event | Confirmed Calendar Date |
|---|---|
| Brokerage Research Note Issued by Motilal Oswal | August 26, 2026 |
| Q2 FY27 Financial Period Concluded | September 30, 2026 |
| Board Meeting & Q2 FY27 Earnings Disclosure | October 28, 2026 |
Financial Performance Snapshot: Q2 FY27 Metrics
The financial scorecard reflects operational expansion in smelter throughput and cost efficiencies. Earnings before interest, tax, depreciation, and amortisation (EBITDA)—a core metric measuring pure operating profitability before non-operating accounting deductions—registered an 83% surge compared to Q2 of the preceding fiscal year.
| Financial Indicator | Reported Value / Growth Metric |
|---|---|
| Net Profit (PAT) | ₹6,187 Crore |
| Net Profit Growth (YoY) | +105% |
| Revenue Growth (YoY) | +41% |
| EBITDA Growth (YoY) | +83% |
| Sequential Net Debt Reduction | ₹3,090 Crore |
Operational Drivers: Volume Expansion & Balance Sheet De-leveraging
According to fundamental reporting across Moneycontrol and Livemint, the sharp recovery in profitability stems from a combination of higher production runs, disciplined input cost management, and robust London Metal Exchange (LME) pricing environments relative to historical troughs. Aluminum smelters benefit significantly from operating leverage; once fixed plant overheads are absorbed, incremental volume output flows straight to operating margins.
A primary focal point for institutional market participants has been balance sheet leverage. In post-demerger trading, the stock experienced volatility, tracking wider industrial commodity corrections. The company addressed debt concerns directly this quarter by lowering net debt by ₹3,090 crore. Net debt represents total interest-bearing borrowings minus available cash and liquid equivalents. Sequentially reducing this figure eases financial carrying costs and frees up internal accruals for ongoing smelter and refinery debottlenecking projects.
The stock’s post-listing trajectory has reflected broader industrial sector swings, as cataloged in our recent IPO listing performance tracker. In a research update from late August, brokerage firm Motilal Oswal pointed to operational scale, integration of captive power sources, and bauxite linkage security as fundamental drivers underpinning cash generation.
Balanced Investor Framework: Growth triggers vs. Downside Risks
Evaluating capital allocation across commodity businesses requires weighing cyclical tailwinds against structural macro variables.
Key Growth triggers
- Aggressive De-leveraging Pace: The ₹3,090 crore sequential debt reduction enhances credit metrics and interest coverage ratios.
- Integrated Smelting Efficiency: Captive power and bauxite logistics help protect per-tonne production costs during commodity swings.
- Strong Operational Leverage: A 41% revenue growth translating into an 83% EBITDA growth demonstrates pricing power and volume efficiency.
Key Downside Risks
- Global Metal Price Sensitivity: Earnings remain directly tethered to benchmark international base metal prices on global exchanges like the LME.
- Raw Material Cost Fluctuations: Shifts in alumina procurement costs or domestic coal linkage availability can narrow operating margins.
- Macroeconomic Volatility: Broader sell-offs across small and mid-cap spaces, as seen during market contractions in late October, can pressure equity valuations regardless of operational execution.
What to Check Before Evaluating Capital Allocation
- Verify debt repayment schedules and quarterly net-debt-to-EBITDA multiples filed on BSE India and NSE India.
- Monitor benchmark global aluminium spot prices and inventory levels across international commodity warehouses.
- Check raw material cost inflation, especially power tariffs and captive alumina integration rates.
- Assess promoter shareholding stability and pledge levels following the group-wide demerger restructuring.
Frequently Asked Questions
What were the core earnings drivers for Vedanta Aluminium in Q2 FY27?
Vedanta Aluminium’s Q2 FY27 net profit grew 105% to ₹6,187 crore, driven primarily by an 83% increase in EBITDA and a 41% rise in operational revenue. Higher sales volumes, disciplined operational overheads, and improved per-tonne metal realisations supported the doubling of bottom-line earnings.
By how much did Vedanta Aluminium reduce its debt this quarter?
The company reduced its net debt by ₹3,090 crore on a quarter-on-quarter sequential basis during Q2 FY27. This de-leveraging was facilitated by strong free cash flow generation from core smelting and refining operations.
Where can investors verify Vedanta Aluminium’s regulatory filings?
Investors can access the full unaudited financial statements, limited review audit reports, and investor presentation slides directly on the official portals of NSE India and BSE India under corporate announcements.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents and quarterly financial filings thoroughly before committing capital. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources referenced: Economic Times, Moneycontrol, Livemint, Motilal Oswal research, BSE India, NSE India filings.
Reusing this article or its images? Credit IPO Bulletin and link to https://ipobulletin.com/2026/10/vedanta-aluminium-q2-profit-jumps.html. Content licence.