
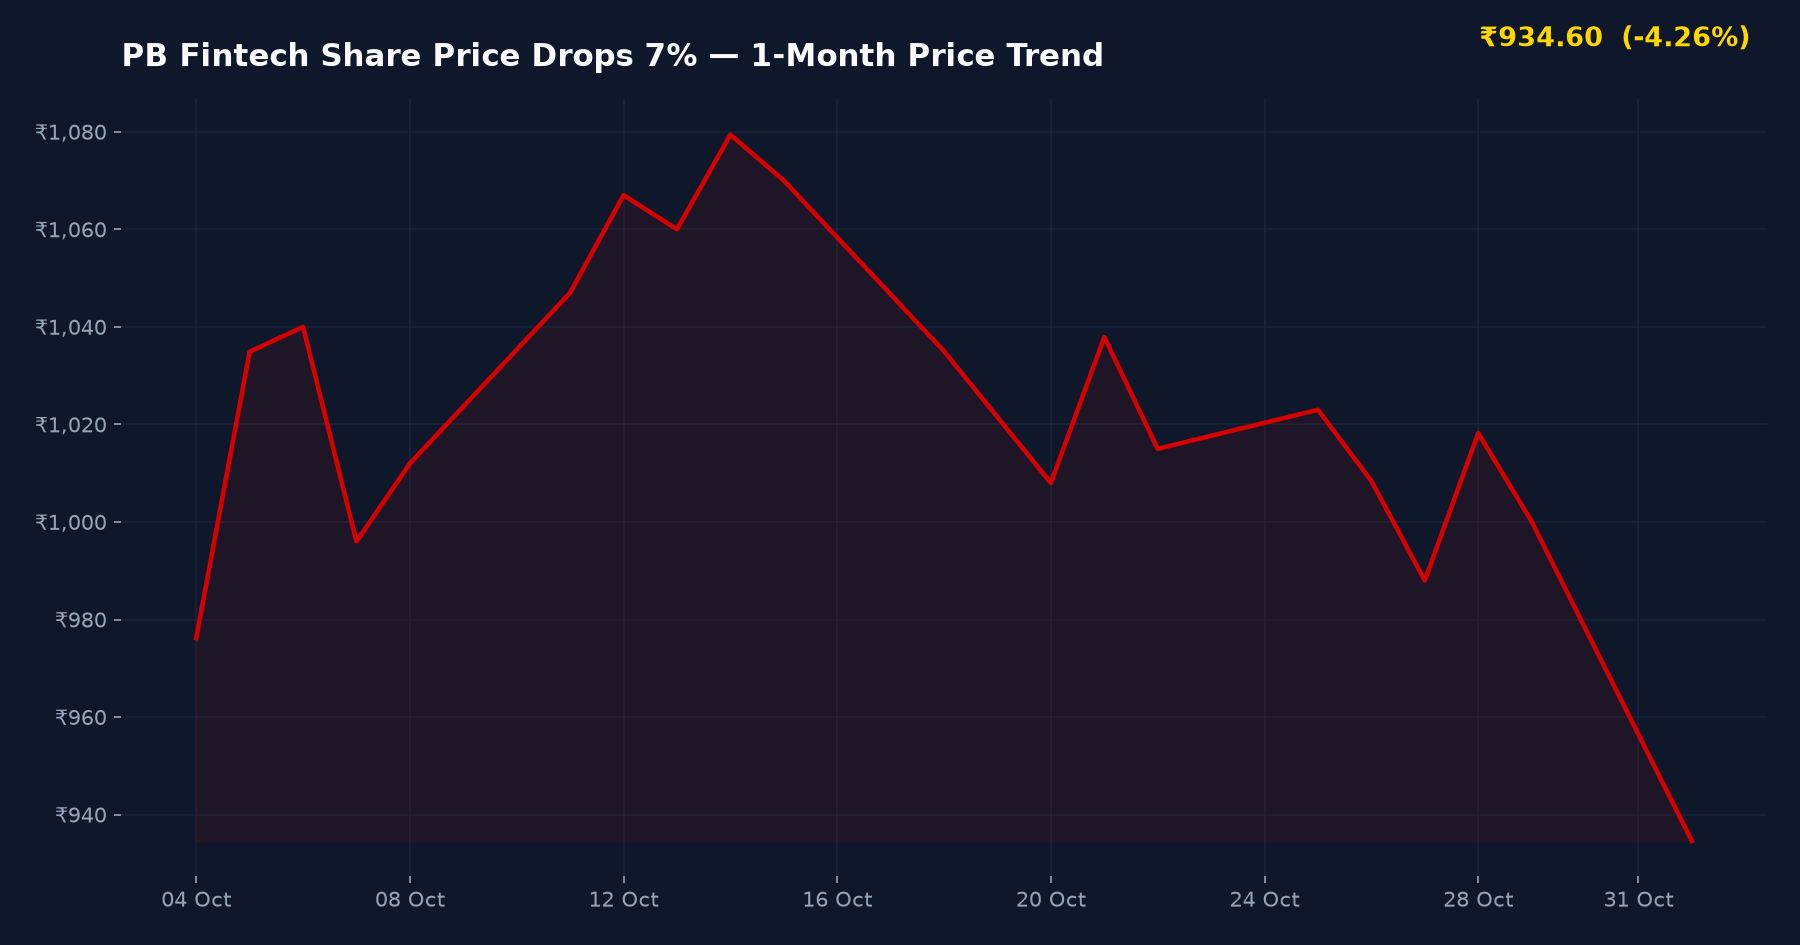
MUMBAI / NEW DELHI, NOVEMBER 02, 2026 — Ahead of Monday’s session, November 02, 2026, shares of PB Fintech Limited slipped 7.0% to touch a 52-week low on the National Stock Exchange (NSE) and BSE, as elevated advertising expenditures offset an otherwise solid operating quarter. The parent company of Policybazaar and Paisabazaar posted a 35% year-on-year (YoY) rise in consolidated revenue to ₹2,178 Crore and a 43% YoY increase in profit after tax (PAT) to ₹192 Crore for the second quarter of FY27, according to regulatory filings submitted to the BSE India and NSE India.
Key Takeaways at a Glance
- Q2 FY27 Operational Delivery: Revenue advanced 35% YoY to ₹2,178 Crore, while net profit grew 43% YoY to ₹192 Crore.
- Market Reaction & Price Pressure: Shares touched a fresh 52-week low following an intraday 7% drop, driven by marketing outlays and ongoing regulatory overhang.
- Institutional Divergence: Global brokerages present contrasting outlooks, with Nomura adjusting its price target to ₹1,100 while Jefferies and Bernstein highlight longer-term earnings resilience.
▼ ₹66.60 (-6.66%)
Day Range: ₹926.60 – ₹1,017.40
52W Range: ₹926.60 – ₹1,964.20
● Real-Time Feed
PB Fintech Timeline & Regulatory triggers Schedule
The market price of PB Fintech has experienced heightened volatility over the past two months following regulatory discussions and financial prints. Tracking these verified corporate and regulatory milestones provides critical context for investors monitoring movements across the Indian market indices dashboard.
| Event / Regulatory triggers | Exact Calendar Date |
|---|---|
| IRDAI Draft Proposals Spark 36% Stock Decline | September 24, 2026 |
| Four-Session Selloff Deepens Total Fall to 43% | September 29, 2026 |
| Nomura Adjusts Target Price to ₹1,100 (Neutral) | October 09, 2026 |
| CEO Clarification on Agent Business Model | October 30, 2026 |
| Q2 FY27 Earnings Impact & 52-Week Low Print | November 02, 2026 |
PB Fintech Q2 FY27 Financial Highlights
PB Fintech’s earnings statement reveals continued expansion in gross transactions across insurance and credit aggregation. Profit after tax (PAT)—representing the company’s net bottom-line earnings after deducting all operating costs, marketing outlays, depreciation, and tax charges—demonstrated robust expansion on an annual basis.
| Financial Metric | Reported Value |
|---|---|
| Operating Revenue (Q2 FY27) | ₹2,178 Crore |
| Revenue Growth (YoY) | 35% |
| Profit After Tax (PAT) (Q2 FY27) | ₹192 Crore |
| Net Profit Growth (YoY) | 43% |
| Intraday Share Price Movement (November 02, 2026) | -7.0% |
Why Advertising Expenditures and Regulatory Uncertainty Pressure the Stock
Despite delivering ₹192 Crore in quarterly bottom-line earnings, market participants reacted negatively to sequential cost dynamics. High customer acquisition costs and branding spends across digital and television media expanded operating expenses during the July-September quarter. While top-line growth remained healthy at 35%, market expectations had factored in faster operating leverage as the platform scales.
Compounding the cost pressure is regulatory scrutiny from the Insurance Regulatory and Development Authority of India (IRDAI). Beginning in late September 2026, the equity saw heavy selling pressure following draft proposals targeting insurance distributor commission structures. On September 24, 2026, the stock tumbled 36% to an 18-month low, extending losses to 43% across four consecutive sessions ending September 29, 2026. Investors evaluating fintech trajectories can review broader context in our recent IPO listing performance tracker.
Speaking on the matter on Friday, October 30, 2026, PB Fintech Chairman and CEO Yashish Dahiya acknowledged that Policybazaar’s point-of-sale agent business may require structural adjustments to align with IRDAI’s evolving regulatory framework. Although management maintains that direct consumer demand on the core portal remains intact, the operational restructuring of offline agent networks has raised questions regarding near-term distribution margins.
Institutional Brokerage Perspectives: Nomura vs. Bernstein and Jefferies
Institutional research desks remain split on PB Fintech’s risk-reward profile following the earnings release and regulatory development:
- Nomura Research: In an equity research note released on October 09, 2026, Nomura cut its target price on PB Fintech to ₹1,100 per share while maintaining a ‘Neutral’ rating, citing uncertainty around insurance commission caps and distribution models.
- Bernstein Institutional View: Conversely, Bernstein analysts noted following the late-September selloff that long-term fundamental drivers remain structurally healthy, suggesting that regulatory concerns may be excessively priced into current multiples.
- Jefferies Coverage: In a multi-sector update published on November 02, 2026, Jefferies identified notable upside potential across select consumer and fintech leaders, including PB Fintech, pointing to sustained digital adoption in non-life and term insurance lines.
Balanced Investor Assessment: Core triggers vs. Downside Risks
Evaluating PB Fintech requires weighing its online market leadership against structural regulatory transitions:
Growth triggers
- Top-Line Execution: Delivered 35% YoY revenue growth in Q2 FY27 to reach ₹2,178 Crore, demonstrating continuous marketplace volume expansion.
- Expanding Net Profit: Reported a 43% YoY increase in consolidated PAT to ₹192 Crore, maintaining positive operating cash flows.
- Dominant Digital Moat: Policybazaar maintains significant market share in digital retail life and health insurance aggregations across India.
Key Downside Risks
- Marketing Outlays: Advertising and promotion costs continue to absorb a substantial portion of gross profit, delaying operating margin expansion.
- IRDAI Regulatory Overhaul: Proposed shifts in commission structures and distributor regulations could alter agent channel profitability.
- Multiple Compression: Persistent regulatory revisions continue to trigger valuation re-ratings across internet platforms.
What to Check Before Evaluating PB Fintech Shares
- Review final circular notifications from IRDAI regarding commission caps on health and general insurance policies.
- Monitor management commentary regarding marketing expenditure efficiency and customer acquisition cost trends in coming quarters.
- Track segmental EBITDA contributions from the core online marketplace versus the newly restructuring agent distribution arm.
- Check institutional shareholding disclosures across mutual fund and foreign portfolio investor filings for changes in institutional sponsorship.
Frequently Asked Questions
Why did PB Fintech shares fall 7% after reporting strong Q2 FY27 results?
PB Fintech shares fell 7% to a 52-week low on November 02, 2026, primarily due to concerns over high advertising spends that weighed on operating margins. Additionally, lingering market apprehension surrounding proposed IRDAI commission rules and agent business modifications kept investor sentiment subdued despite 35% revenue growth and 43% PAT expansion.
What were PB Fintech’s key financial results for Q2 FY27?
In the second quarter of FY27, PB Fintech reported consolidated revenue from operations of ₹2,178 Crore, representing a 35% year-on-year increase from the corresponding quarter of the previous fiscal year. Consolidated profit after tax (PAT) rose 43% year-on-year to ₹192 Crore.
How are IRDAI draft proposals affecting Policybazaar’s business model?
The IRDAI draft guidelines focus on regulating commissions and distribution fees paid to insurance intermediaries. While Policybazaar’s core direct-to-consumer digital marketplace remains fundamentally sound, CEO Yashish Dahiya indicated on October 30, 2026, that the company’s offline agent distribution business may need structural realignment under the proposed regulatory changes.
SEBI Compliance & Statutory Disclaimer
The information and analysis presented on IPO Bulletin (ipobulletin.com) are for informational and educational purposes only and do not constitute financial, investment, or legal advice. Securities market investments are subject to market risks; please read all offer documents (DRHP/RHP) thoroughly before committing capital. Grey Market Premium (GMP) figures are unofficial, unregulated street estimates. Always consult a SEBI-registered investment advisor before making financial decisions.
Sources referenced: Moneycontrol, Business Standard, Livemint, Business Today, BSE India, NSE India
Reusing this article or its images? Credit IPO Bulletin and link to https://ipobulletin.com/news/pb-fintech-share-price-drops/. Content licence.